Buy financetip.eu ?
We are moving the project
financetip.eu .
Are you interested in purchasing the domain
financetip.eu ?
domain@kv-gmbh.de · 0541-91531010
Buy financetip.eu ?
Who already knows the Cashflow Quadrant?
The Cashflow Quadrant is a concept popularized by Robert Kiyosaki in his book "Rich Dad Poor Dad." Many people who have read Kiyosaki's book or have attended his seminars are familiar with the Cashflow Quadrant. Additionally, individuals who are interested in personal finance, entrepreneurship, and wealth building may also be familiar with the concept. It is often discussed in financial education and business circles. **
Why is the social board game Cashflow so expensive?
The social board game Cashflow is expensive because it is a premium product that offers a unique and educational experience. The game is designed to teach players about financial literacy and investing, and it comes with high-quality components and materials. Additionally, the game is produced in limited quantities, which can drive up the price due to the higher production costs. The brand and reputation of the game also contribute to its high price, as it is known for its high value and impact on financial education. **
Similar search terms for Cashflow
Top-Angebote
Products related to Cashflow:
-
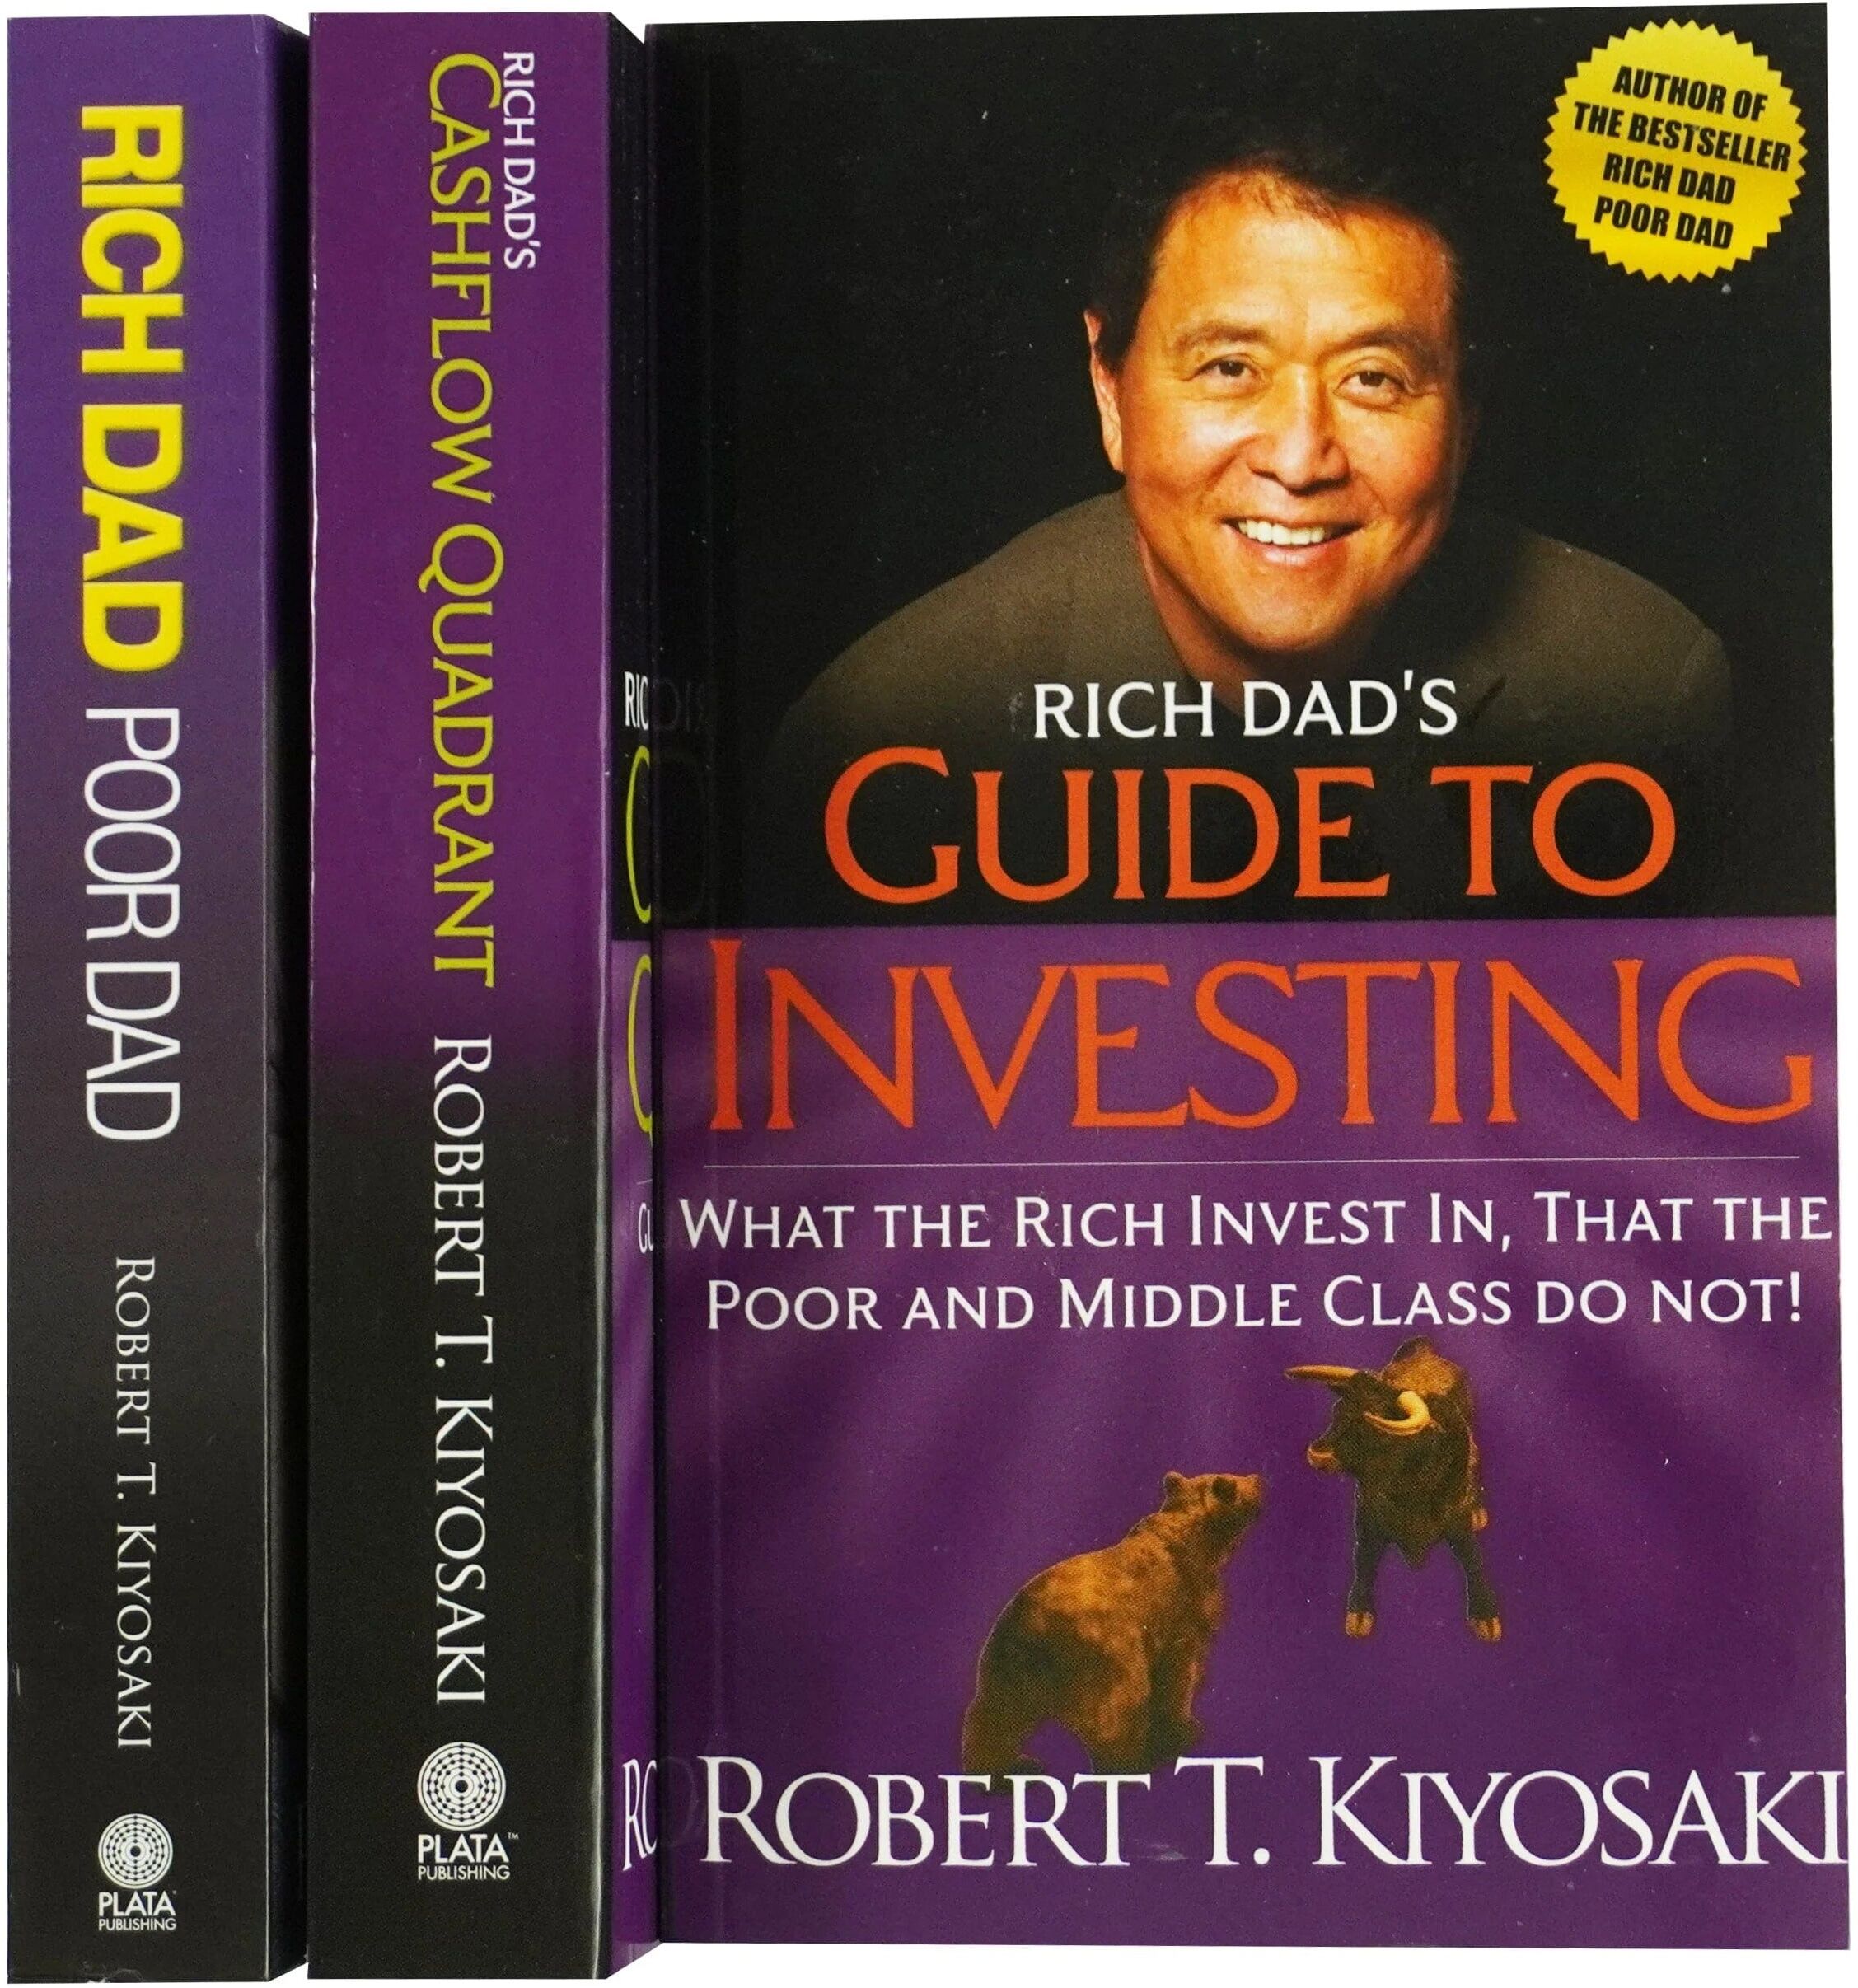
Plata Publishing Robert T. Kiyosaki 3 Books Collection Set (Rich Dad's Cashflow Quadrant, Rich Dad's Guide to Investing, Why the Rich are Getting Richer)Take control of your financial future with this powerful 3-book collection set by Robert T. Kiyosaki, one of the most influential voices in financial education. This essential bundle includes: Rich Dad’s Cashflow Quadrant – Understand the four types of income earners and how to move toward financial independence. Rich Dad’s Guide to Investing – Learn the mindset and strategies used by wealthy investors. Why the Rich Are Getting Richer – Discover how financial education and modern economic shifts impact wealth-building. Together, these books provide a comprehensive guide to financial literacy, investing, and wealth creation, helping readers shift their mindset from working for money to making money work for them. Why Readers Love This Collection: Includes 3 bestselling Rich Dad books Focus on financial independence and investing mindset Easy-to-understand concepts for beginners Practical insights into building long-term wealth Ideal for entrepreneurs, investors, and self-improvement readers A must-have for anyone serious about improving their financial knowledge, this collection offers a roadmap to smarter money decisions and long-term success.12,99 £*Shipping: 2,99 £Secure redirect to the provider
-
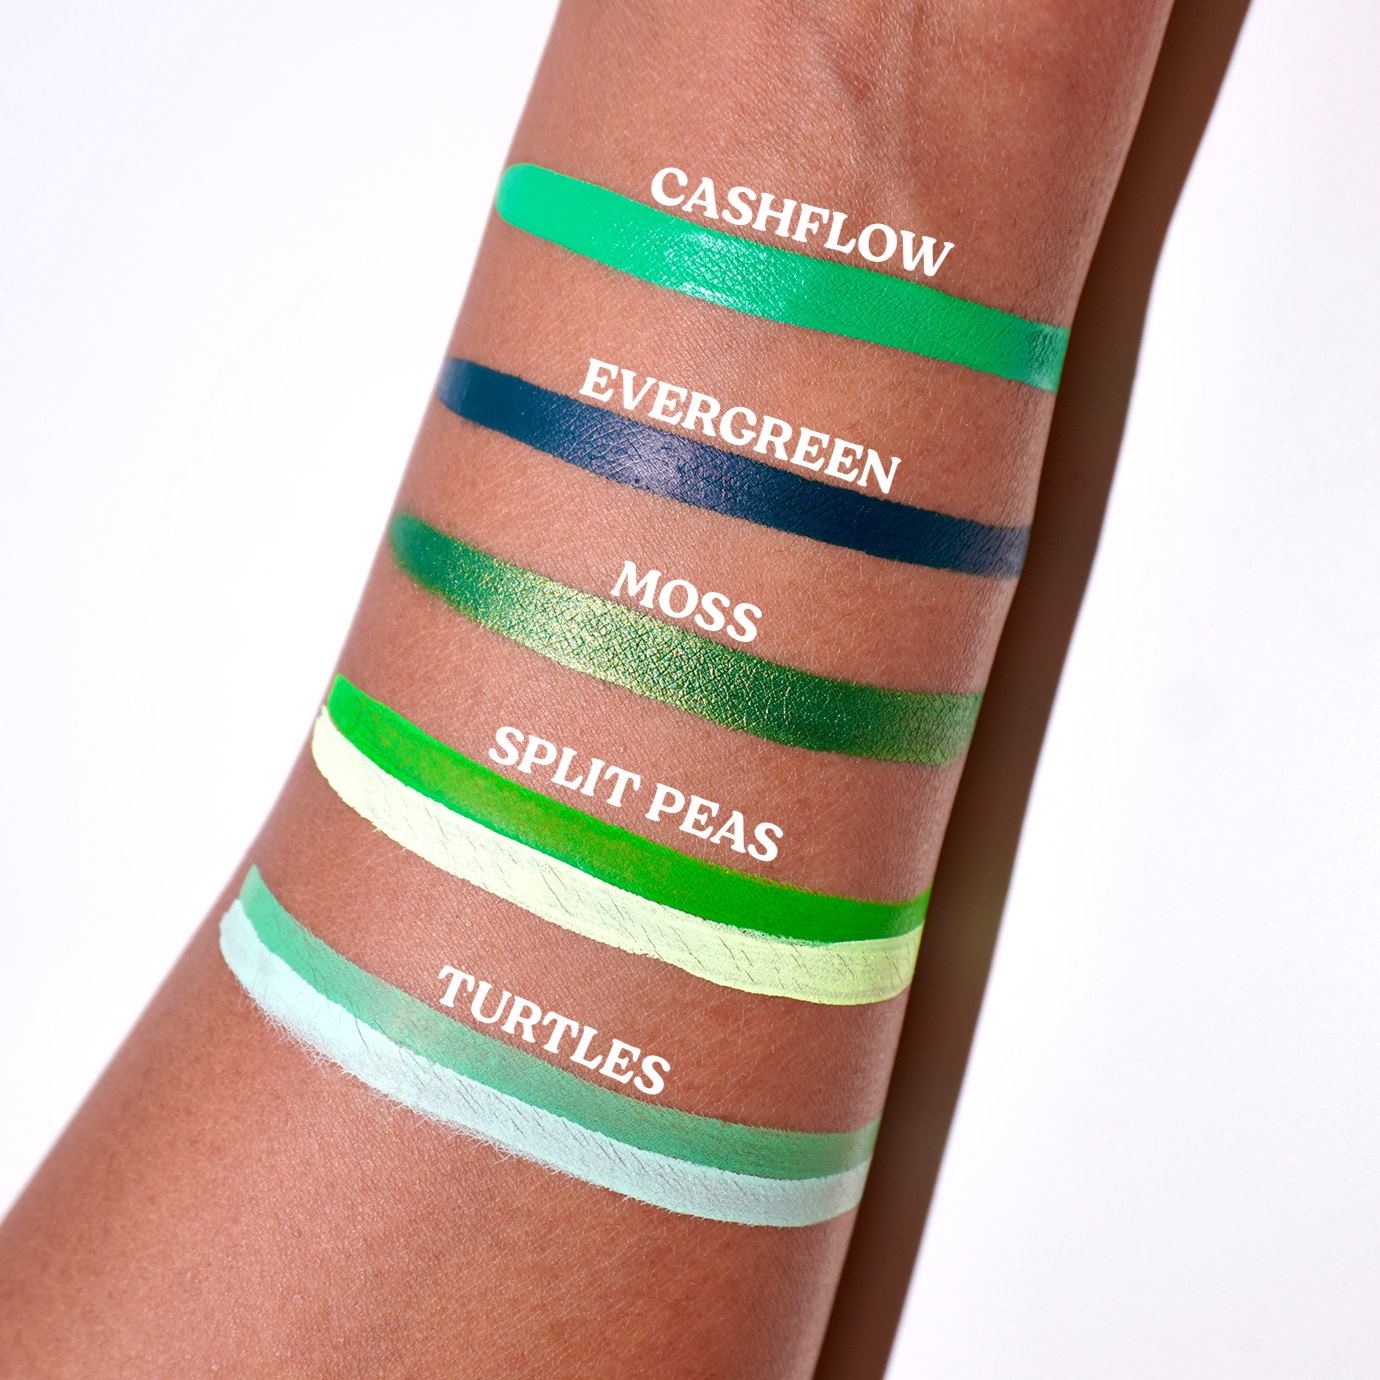
Cashflow (Green Matte) Wet Liner® - Eyeliner - Glisten Cosmetics Small - 3gDescription. Create vibrant looks with our Wet Liners! These small but mighty eyeliners pack a punch with full-colour payoff that won't crack or fade. Step up your look without breaking the bank!. How to use: Open lid, add a small amount of water to lid, dip brush into water (not too much) and then swirl the brush into the pigment and watch the colour pay off!. Cashflow - True Green. Product Info. For external use only. Keep it at room temperature, avoid placing in direct sunlight. Avoid direct contact with eyes and keep out of reach of children. Discontinue use if signs of irritation or rash appear. If you are allergic, or are under treatment/medication for any skin or hair disorders, you must consult with your healthcare professional before using any of our products. To check for skin sensitivity do a small patch test on inner elbow. Glisten Cosmetics will not be held responsible for any reactions that occur due to the customer not taking due care.. All sales are subject to UK & EU law.. Please read our disclaimer before purchasing.. INGREDIENTS: Aqua, Glycerin, Polysorbate-20, Acacia Senegal Gum, Phenoxyethanol, Methylparaben. May contain (+/•) Sericite, Mica, Talc, Calcium Carbonate, Titanium Dioxide (CI 77891). FDC Yellow 10 (CI 47005), FDC Yellow 11 (CI 47000). FDC Blue 1 (CI 42090). D&C; Violet 2 EXT (CI60730). DC Red 22 (CI 45380). DC Red 28 (CI 45410), IRON OXIDES BLACK (CI 77499). Net Weight 3g/10g. Once opened use within 18 months. Notice: Some colours contain pigments, which according to US law may not be suitable for use in the eye area.7,00 £*Shipping: 4,00 £Secure redirect to the provider


-
What is the flexible budgeting 2?
Flexible budgeting 2 is a budgeting approach that allows for adjustments to the budget based on changes in activity levels. It is an improvement over the original flexible budgeting method, as it takes into account different levels of activity and adjusts the budget accordingly. This allows for better planning and decision-making, as it provides a more accurate representation of costs and revenues at different levels of production or sales. Flexible budgeting 2 is particularly useful for businesses with fluctuating activity levels, as it helps to better manage resources and expenses. **
-
Can someone help me with business administration budgeting?
Yes, there are many resources available to help with business administration budgeting. You can seek assistance from financial advisors, accountants, or business consultants who specialize in budgeting and financial planning. Additionally, there are numerous online courses, workshops, and books that can provide guidance and practical tips for creating and managing a business budget. It's important to seek out help from professionals or resources that are tailored to your specific industry and business needs. **
-
Should teenagers be required to start saving for retirement at a young age? What arguments support this?
Yes, teenagers should be encouraged to start saving for retirement at a young age. By starting early, they can take advantage of compound interest and have more time for their savings to grow. It also instills good financial habits and responsibility from a young age, ensuring they are better prepared for their future. Additionally, with the uncertainty surrounding the future of social security and pensions, it is important for teenagers to take control of their own financial future. **
-
Why are value-added taxes considered indirect taxes and income taxes considered direct taxes?
Value-added taxes are considered indirect taxes because they are imposed on the consumption of goods and services, and the burden of the tax is ultimately passed on to the consumer through higher prices. On the other hand, income taxes are considered direct taxes because they are levied directly on individuals and businesses based on their income, and the burden of the tax cannot be shifted to someone else. This distinction is based on how the taxes are collected and who ultimately bears the economic burden of the tax. **


When is retirement?
Retirement typically occurs when an individual reaches a certain age, which is often around 65 years old. However, retirement can also be influenced by factors such as financial readiness, health considerations, and personal preferences. Some people choose to retire earlier or later than the traditional age, depending on their individual circumstances and goals. Ultimately, retirement is a personal decision that varies for each individual. **
Is retirement mandatory?
Retirement is not mandatory in most countries. It is a personal choice based on individual circumstances, financial readiness, and personal preferences. Some people choose to continue working past the traditional retirement age for various reasons, such as staying active, pursuing a passion, or maintaining social connections. However, some professions or industries may have mandatory retirement ages due to safety concerns or physical demands. **
Top-Angebote
Products related to Cashflow:
-
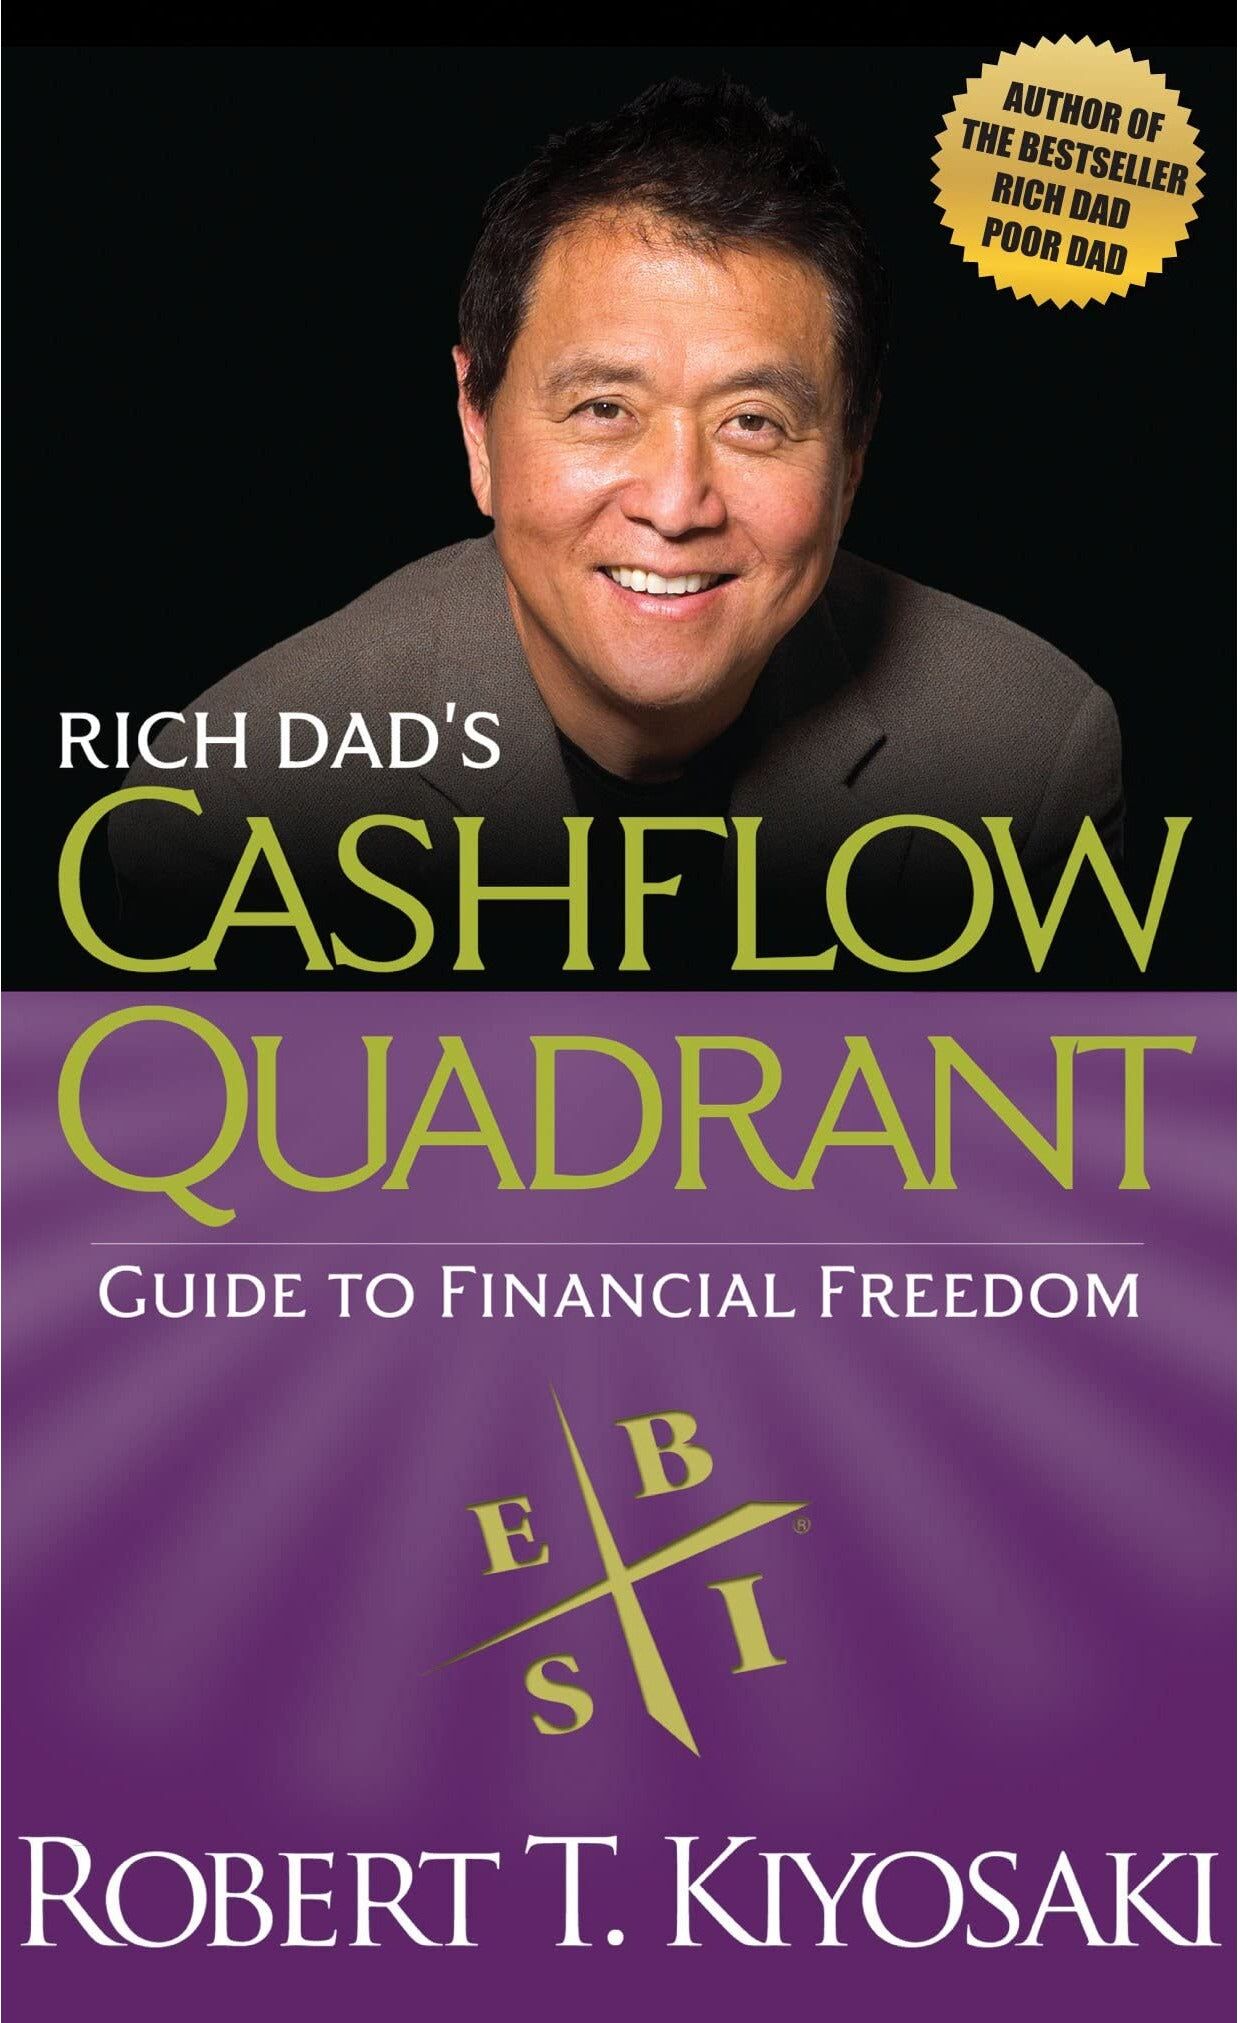
Plata Publishing Rich Dad’s Cashflow Quadrant – Robert T. Kiyosaki Guide to Financial Freedom, Investing & Wealth BuildingDiscover why some people work harder for money while others make money work for them with Rich Dad’s Cashflow Quadrant by Robert T. Kiyosaki. In this powerful follow-up to Rich Dad Poor Dad, Kiyosaki introduces the Cashflow Quadrant, a simple yet transformative framework that explains the four ways people earn income: Employee (E), Self-Employed (S), Business Owner (B), and Investor (I). The book reveals why true financial freedom is most often found on the B and I side of the quadrant. Through real-world examples and practical insights, Kiyosaki teaches readers how to shift their mindset, reduce financial risk, and build sustainable wealth through business ownership and investing. This book focuses on financial intelligence, passive income, and long-term wealth creation, rather than short-term gains. What You’ll Learn: The meaning of the Cashflow Quadrant (E, S, B, I) Why employees and self-employed people face financial limits How business owners and investors build passive income The mindset shifts required for financial independence How to move from job-based income to asset-based income Ideal for anyone serious about financial freedom, investing, and entrepreneurship, Rich Dad’s Cashflow Quadrant is a must-read personal finance classic.4,99 £*Shipping: 1,99 £Secure redirect to the provider
-
Plata Publishing Robert T. Kiyosaki Classics 3 Books Collection Box Set (Rich Dad Poor Dad, Cashflow Quadrant, Guide to Investing)Rich Dads Guide To Investing Investing means different things to different people… and there is a huge difference between passive investing and becoming an active, engaged investor. Rich Dad’s Guide to Investing, one of the three core titles in the Rich Dad Series, covers the basic rules of investing, how to reduce your investment risk, how to convert your earned income into passive income… plus Rich Dad’s 10 Investor Controls. Rich Dads Cashflow Quadrant Tired of living paycheck to paycheck? Learn why some people work less but earn more. Pay less in taxes, and learn to make their money work for them. It's simply knowing which quadrant to work from ― and when. The wealthy know that the keys to wealth and financial freedom are found on the right side of the quadrant, through business and investing. Rich Dad Poor Dad Rich Dad Poor Dad is Robert's story of growing up with two dads — his real father and the father of his best friend, his rich dad — and the ways in which both men shaped his thoughts about money and investing. The book explodes the myth that you need to earn a high income to be rich and explains the difference between working for money and having your money work for you. In many ways, the messages of Rich Dad Poor Dad, messages that were challenged and criticized 25 ago, are more meaningful, relevant, and important today than ever.11,89 £*Shipping: 2,99 £Secure redirect to the provider
-
Plata Publishing Robert T. Kiyosaki 3 Books Collection Set (Rich Dad's Cashflow Quadrant, Rich Dad's Guide to Investing, Why the Rich are Getting Richer)Take control of your financial future with this powerful 3-book collection set by Robert T. Kiyosaki, one of the most influential voices in financial education. This essential bundle includes: Rich Dad’s Cashflow Quadrant – Understand the four types of income earners and how to move toward financial independence. Rich Dad’s Guide to Investing – Learn the mindset and strategies used by wealthy investors. Why the Rich Are Getting Richer – Discover how financial education and modern economic shifts impact wealth-building. Together, these books provide a comprehensive guide to financial literacy, investing, and wealth creation, helping readers shift their mindset from working for money to making money work for them. Why Readers Love This Collection: Includes 3 bestselling Rich Dad books Focus on financial independence and investing mindset Easy-to-understand concepts for beginners Practical insights into building long-term wealth Ideal for entrepreneurs, investors, and self-improvement readers A must-have for anyone serious about improving their financial knowledge, this collection offers a roadmap to smarter money decisions and long-term success.12,99 £*Shipping: 2,99 £Secure redirect to the provider
-
Cashflow (Green Matte) Wet Liner® - Eyeliner - Glisten Cosmetics Small - 3gDescription. Create vibrant looks with our Wet Liners! These small but mighty eyeliners pack a punch with full-colour payoff that won't crack or fade. Step up your look without breaking the bank!. How to use: Open lid, add a small amount of water to lid, dip brush into water (not too much) and then swirl the brush into the pigment and watch the colour pay off!. Cashflow - True Green. Product Info. For external use only. Keep it at room temperature, avoid placing in direct sunlight. Avoid direct contact with eyes and keep out of reach of children. Discontinue use if signs of irritation or rash appear. If you are allergic, or are under treatment/medication for any skin or hair disorders, you must consult with your healthcare professional before using any of our products. To check for skin sensitivity do a small patch test on inner elbow. Glisten Cosmetics will not be held responsible for any reactions that occur due to the customer not taking due care.. All sales are subject to UK & EU law.. Please read our disclaimer before purchasing.. INGREDIENTS: Aqua, Glycerin, Polysorbate-20, Acacia Senegal Gum, Phenoxyethanol, Methylparaben. May contain (+/•) Sericite, Mica, Talc, Calcium Carbonate, Titanium Dioxide (CI 77891). FDC Yellow 10 (CI 47005), FDC Yellow 11 (CI 47000). FDC Blue 1 (CI 42090). D&C; Violet 2 EXT (CI60730). DC Red 22 (CI 45380). DC Red 28 (CI 45410), IRON OXIDES BLACK (CI 77499). Net Weight 3g/10g. Once opened use within 18 months. Notice: Some colours contain pigments, which according to US law may not be suitable for use in the eye area.7,00 £*Shipping: 4,00 £Secure redirect to the provider
-
Who already knows the Cashflow Quadrant?
The Cashflow Quadrant is a concept popularized by Robert Kiyosaki in his book "Rich Dad Poor Dad." Many people who have read Kiyosaki's book or have attended his seminars are familiar with the Cashflow Quadrant. Additionally, individuals who are interested in personal finance, entrepreneurship, and wealth building may also be familiar with the concept. It is often discussed in financial education and business circles. **
-
Why is the social board game Cashflow so expensive?
The social board game Cashflow is expensive because it is a premium product that offers a unique and educational experience. The game is designed to teach players about financial literacy and investing, and it comes with high-quality components and materials. Additionally, the game is produced in limited quantities, which can drive up the price due to the higher production costs. The brand and reputation of the game also contribute to its high price, as it is known for its high value and impact on financial education. **
-
What is the flexible budgeting 2?
Flexible budgeting 2 is a budgeting approach that allows for adjustments to the budget based on changes in activity levels. It is an improvement over the original flexible budgeting method, as it takes into account different levels of activity and adjusts the budget accordingly. This allows for better planning and decision-making, as it provides a more accurate representation of costs and revenues at different levels of production or sales. Flexible budgeting 2 is particularly useful for businesses with fluctuating activity levels, as it helps to better manage resources and expenses. **
-
Can someone help me with business administration budgeting?
Yes, there are many resources available to help with business administration budgeting. You can seek assistance from financial advisors, accountants, or business consultants who specialize in budgeting and financial planning. Additionally, there are numerous online courses, workshops, and books that can provide guidance and practical tips for creating and managing a business budget. It's important to seek out help from professionals or resources that are tailored to your specific industry and business needs. **
Similar search terms for Cashflow
-
Penguin Rule #1: The Simple Strategy for Successful Investing in Only 15 Minutes a WeekPhil Town doesn't think so. He made a fortune, and in Rule #1 he'll show you how he did it.Rule #1:- Sets out the five key numbers that really count when you're buying stocks and shares- Explains how to use new Internet tools to simplify research- Shows how to exploit the advantages of being an individual investor- Demonstrates how to pay fifty pence for every pound's worth of business6,70 £*Shipping: 2,99 £Secure redirect to the provider
-
Perfect Picks Market Portable Outdoor Solar Fire Starter Card Credit Card Sized Fresnel Lens Survival Tool Portable Outdoor Solar Fire Starter Card Credit Card Sized Fresnel Lens Survival ToolImagine having reliable fire anywhere the sun shines without matches or fuel. The solar fire starter card is a compact, walletfriendly survival essential that harnesses the power of sunshine to ignite tinder fast. Designed for campers, hikers, and...29,97 $*Shipping: 0,00 $Secure redirect to the provider
-
Should teenagers be required to start saving for retirement at a young age? What arguments support this?
Yes, teenagers should be encouraged to start saving for retirement at a young age. By starting early, they can take advantage of compound interest and have more time for their savings to grow. It also instills good financial habits and responsibility from a young age, ensuring they are better prepared for their future. Additionally, with the uncertainty surrounding the future of social security and pensions, it is important for teenagers to take control of their own financial future. **
-
Why are value-added taxes considered indirect taxes and income taxes considered direct taxes?
Value-added taxes are considered indirect taxes because they are imposed on the consumption of goods and services, and the burden of the tax is ultimately passed on to the consumer through higher prices. On the other hand, income taxes are considered direct taxes because they are levied directly on individuals and businesses based on their income, and the burden of the tax cannot be shifted to someone else. This distinction is based on how the taxes are collected and who ultimately bears the economic burden of the tax. **
-
When is retirement?
Retirement typically occurs when an individual reaches a certain age, which is often around 65 years old. However, retirement can also be influenced by factors such as financial readiness, health considerations, and personal preferences. Some people choose to retire earlier or later than the traditional age, depending on their individual circumstances and goals. Ultimately, retirement is a personal decision that varies for each individual. **
-
Is retirement mandatory?
Retirement is not mandatory in most countries. It is a personal choice based on individual circumstances, financial readiness, and personal preferences. Some people choose to continue working past the traditional retirement age for various reasons, such as staying active, pursuing a passion, or maintaining social connections. However, some professions or industries may have mandatory retirement ages due to safety concerns or physical demands. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.