Buy financetip.eu ?
We are moving the project
financetip.eu .
Are you interested in purchasing the domain
financetip.eu ?
domain@kv-gmbh.de · 0541-91531010
Buy financetip.eu ?
How to calculate the annual annuity?
To calculate the annual annuity, you can use the formula: Annual Annuity = Initial Investment / Present Value Factor Where: - Initial Investment is the amount of money invested or the principal amount - Present Value Factor is calculated based on the interest rate and the number of periods You can also use online calculators or financial software to help you determine the annual annuity based on your specific investment details. **
When do you use the future value of an annuity and when do you use the present value of an annuity?
You would use the future value of an annuity when you want to calculate the total value of a series of equal cash flows at a specific point in the future. This is useful when planning for long-term financial goals or investments. On the other hand, you would use the present value of an annuity when you want to determine the current value of a series of equal cash flows that will be received or paid in the future. This is helpful when evaluating the worth of an investment or deciding on the affordability of a loan. **

Similar search terms for Annuity
Top-Angebote
Products related to Annuity:
-
Penguin Rule #1: The Simple Strategy for Successful Investing in Only 15 Minutes a WeekPhil Town doesn't think so. He made a fortune, and in Rule #1 he'll show you how he did it.Rule #1:- Sets out the five key numbers that really count when you're buying stocks and shares- Explains how to use new Internet tools to simplify research- Shows how to exploit the advantages of being an individual investor- Demonstrates how to pay fifty pence for every pound's worth of business6,70 £*Shipping: 2,99 £Secure redirect to the provider
-
Plata Publishing Rich Dad’s Cashflow Quadrant – Robert T. Kiyosaki Guide to Financial Freedom, Investing & Wealth BuildingDiscover why some people work harder for money while others make money work for them with Rich Dad’s Cashflow Quadrant by Robert T. Kiyosaki. In this powerful follow-up to Rich Dad Poor Dad, Kiyosaki introduces the Cashflow Quadrant, a simple yet transformative framework that explains the four ways people earn income: Employee (E), Self-Employed (S), Business Owner (B), and Investor (I). The book reveals why true financial freedom is most often found on the B and I side of the quadrant. Through real-world examples and practical insights, Kiyosaki teaches readers how to shift their mindset, reduce financial risk, and build sustainable wealth through business ownership and investing. This book focuses on financial intelligence, passive income, and long-term wealth creation, rather than short-term gains. What You’ll Learn: The meaning of the Cashflow Quadrant (E, S, B, I) Why employees and self-employed people face financial limits How business owners and investors build passive income The mindset shifts required for financial independence How to move from job-based income to asset-based income Ideal for anyone serious about financial freedom, investing, and entrepreneurship, Rich Dad’s Cashflow Quadrant is a must-read personal finance classic.4,99 £*Shipping: 1,99 £Secure redirect to the provider
-
Perfect Picks Market Portable Outdoor Solar Fire Starter Card Credit Card Sized Fresnel Lens Survival Tool Portable Outdoor Solar Fire Starter Card Credit Card Sized Fresnel Lens Survival ToolImagine having reliable fire anywhere the sun shines without matches or fuel. The solar fire starter card is a compact, walletfriendly survival essential that harnesses the power of sunshine to ignite tinder fast. Designed for campers, hikers, and...29,97 $*Shipping: 0,00 $Secure redirect to the provider
-
Uplifted Finds Stainless Steel Credit Card Size Bottle Opener Playing Card Design blackOpen bottles in style with this sleek stainless steel bottle opener designed in a credit card size with a unique playing card design. The slim, durable metal fits easily into your wallet or travel bag, making it perfect for outdoor events, parties,...61,97 $*Shipping: 0,00 $Secure redirect to the provider



-
What is the relationship between annuity and present value?
An annuity is a series of equal payments made at regular intervals, while present value is the current value of a future sum of money, discounted at a specific rate. The relationship between annuity and present value is that the present value of an annuity is the current worth of all the future cash flows from the annuity, discounted back to the present time. In other words, the present value represents the total value of all the future payments from the annuity if they were all received today. **
-
How can the annuity formula be rearranged for n?
The annuity formula can be rearranged for n by isolating the variable n on one side of the equation. The annuity formula is A = P * [(1 - (1 + r)^(-n)) / r], where A is the future value of the annuity, P is the periodic payment, r is the interest rate, and n is the number of periods. To solve for n, we can rearrange the formula to isolate n on one side: n = -log(1 - (A * r) / P) / log(1 + r). This rearranged formula allows us to solve for the number of periods required to achieve a certain future value given the periodic payment and interest rate. **
-
How to calculate the annuity in the following problem?
To calculate the annuity in a problem, you would use the formula A = P * (1 - (1 + r)^-n) / r, where A is the annuity, P is the periodic payment, r is the interest rate, and n is the number of periods. First, determine the periodic payment, which is the amount of money paid or received at regular intervals. Then, calculate the interest rate and the number of periods. Finally, plug these values into the formula to find the annuity. **
-
What are the advantages and disadvantages of an annuity loan?
Annuity loans have the advantage of providing a predictable payment schedule, which can make budgeting easier for borrowers. Additionally, the interest rate is fixed, providing stability in the cost of borrowing. However, a disadvantage of annuity loans is that the interest payments are front-loaded, meaning that a larger portion of the payment goes towards interest in the early years of the loan. This can result in slower equity build-up in the early years of the loan. Additionally, if interest rates decrease, borrowers may miss out on potential savings as they are locked into a fixed interest rate. **
How do you calculate a variable interest rate annuity loan?
To calculate a variable interest rate annuity loan, you would first need to determine the initial loan amount, the interest rate, and the length of the loan. Then, you would need to calculate the periodic payment using the annuity formula, which takes into account the interest rate and the number of periods. The interest rate for a variable annuity loan may change over time, so you would need to use the current interest rate for each calculation. It's important to keep in mind that the total amount paid over the life of the loan will depend on how the interest rate fluctuates. **
What is the derivation of the formula for the annuity factor?
The formula for the annuity factor is derived from the present value formula for an ordinary annuity. The present value of an ordinary annuity is calculated by discounting each cash flow back to its present value and summing them up. The annuity factor is the result of this calculation, representing the factor by which the periodic cash flow needs to be multiplied to calculate the present value of the annuity. The formula takes into account the interest rate, number of periods, and the frequency of payments to determine the annuity factor. **
Top-Angebote
Products related to Annuity:
-
Penguin Rule #1: The Simple Strategy for Successful Investing in Only 15 Minutes a WeekPhil Town doesn't think so. He made a fortune, and in Rule #1 he'll show you how he did it.Rule #1:- Sets out the five key numbers that really count when you're buying stocks and shares- Explains how to use new Internet tools to simplify research- Shows how to exploit the advantages of being an individual investor- Demonstrates how to pay fifty pence for every pound's worth of business6,70 £*Shipping: 2,99 £Secure redirect to the provider
-
Plata Publishing Rich Dad’s Cashflow Quadrant – Robert T. Kiyosaki Guide to Financial Freedom, Investing & Wealth BuildingDiscover why some people work harder for money while others make money work for them with Rich Dad’s Cashflow Quadrant by Robert T. Kiyosaki. In this powerful follow-up to Rich Dad Poor Dad, Kiyosaki introduces the Cashflow Quadrant, a simple yet transformative framework that explains the four ways people earn income: Employee (E), Self-Employed (S), Business Owner (B), and Investor (I). The book reveals why true financial freedom is most often found on the B and I side of the quadrant. Through real-world examples and practical insights, Kiyosaki teaches readers how to shift their mindset, reduce financial risk, and build sustainable wealth through business ownership and investing. This book focuses on financial intelligence, passive income, and long-term wealth creation, rather than short-term gains. What You’ll Learn: The meaning of the Cashflow Quadrant (E, S, B, I) Why employees and self-employed people face financial limits How business owners and investors build passive income The mindset shifts required for financial independence How to move from job-based income to asset-based income Ideal for anyone serious about financial freedom, investing, and entrepreneurship, Rich Dad’s Cashflow Quadrant is a must-read personal finance classic.4,99 £*Shipping: 1,99 £Secure redirect to the provider
-
How to calculate the annual annuity?
To calculate the annual annuity, you can use the formula: Annual Annuity = Initial Investment / Present Value Factor Where: - Initial Investment is the amount of money invested or the principal amount - Present Value Factor is calculated based on the interest rate and the number of periods You can also use online calculators or financial software to help you determine the annual annuity based on your specific investment details. **
-
When do you use the future value of an annuity and when do you use the present value of an annuity?
You would use the future value of an annuity when you want to calculate the total value of a series of equal cash flows at a specific point in the future. This is useful when planning for long-term financial goals or investments. On the other hand, you would use the present value of an annuity when you want to determine the current value of a series of equal cash flows that will be received or paid in the future. This is helpful when evaluating the worth of an investment or deciding on the affordability of a loan. **
-
What is the relationship between annuity and present value?
An annuity is a series of equal payments made at regular intervals, while present value is the current value of a future sum of money, discounted at a specific rate. The relationship between annuity and present value is that the present value of an annuity is the current worth of all the future cash flows from the annuity, discounted back to the present time. In other words, the present value represents the total value of all the future payments from the annuity if they were all received today. **
-
How can the annuity formula be rearranged for n?
The annuity formula can be rearranged for n by isolating the variable n on one side of the equation. The annuity formula is A = P * [(1 - (1 + r)^(-n)) / r], where A is the future value of the annuity, P is the periodic payment, r is the interest rate, and n is the number of periods. To solve for n, we can rearrange the formula to isolate n on one side: n = -log(1 - (A * r) / P) / log(1 + r). This rearranged formula allows us to solve for the number of periods required to achieve a certain future value given the periodic payment and interest rate. **
Similar search terms for Annuity
-
Perfect Picks Market Portable Outdoor Solar Fire Starter Card Credit Card Sized Fresnel Lens Survival Tool Portable Outdoor Solar Fire Starter Card Credit Card Sized Fresnel Lens Survival ToolImagine having reliable fire anywhere the sun shines without matches or fuel. The solar fire starter card is a compact, walletfriendly survival essential that harnesses the power of sunshine to ignite tinder fast. Designed for campers, hikers, and...29,97 $*Shipping: 0,00 $Secure redirect to the provider
-
Uplifted Finds Stainless Steel Credit Card Size Bottle Opener Playing Card Design blackOpen bottles in style with this sleek stainless steel bottle opener designed in a credit card size with a unique playing card design. The slim, durable metal fits easily into your wallet or travel bag, making it perfect for outdoor events, parties,...61,97 $*Shipping: 0,00 $Secure redirect to the provider
-
Uplifted Trends Stainless Steel Playing Cards Bottle Opener Credit Card Beer Opener blackUnlock the fun with our Stainless Steel Playing Cards Bottle Opener, designed for both style and function. Whether you're a winemaker, beer enthusiast, or lover of unique bar tools, this opener is perfect for you. Crafted from highquality stainless...29,97 $*Shipping: 0,00 $Secure redirect to the provider
-
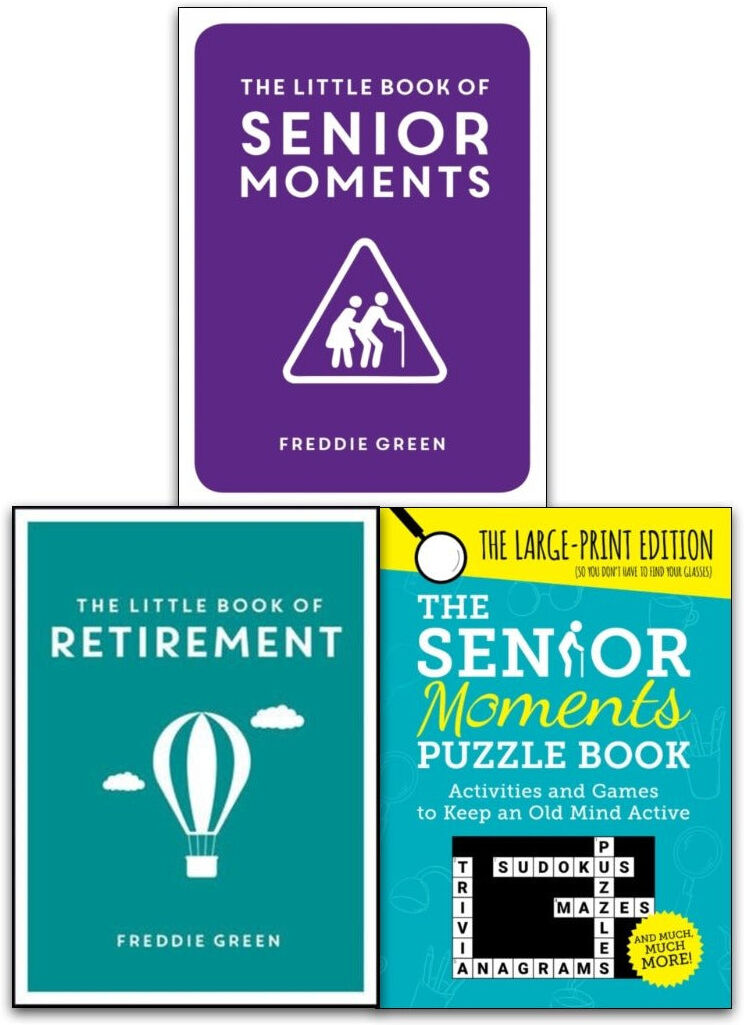
Summersdale Publishers The Little Book of Senior Moments, The Little Book of Retirement, The Senior Moments Puzzle 3 Books Collection SetTitles in the Set Are: The Little Book of Senior Moments The Little Book of Retirement The Senior Moments Puzzle Book The Little Book of Senior Moments You know you are having a senior moment when you decide it is time to pull up your socks, and realise you forgot to put any on If this sounds all too familiar, read on to discover whether your marbles just need a spring clean or you've well and truly lost them. The Little Book of Retirement You know you are retired when People from work keep phoning up asking where on earth you put important documents. The joys of retirement are many and varied, so read on to discover what makes these golden years so golden. The Senior Moments Puzzle Book Instead of wracking your brain for something to do, challenge your mind and have hours of fun with this delightful puzzle book. With everything from tricky crosswords, word searches, anagram puzzles and sudokus to simpler brain-teasers such as spot the differences, mazes and trivia questions, this large book edition means you will not even need your glasses wherever you put them.9,95 £*Shipping: 2,99 £Secure redirect to the provider
-
How to calculate the annuity in the following problem?
To calculate the annuity in a problem, you would use the formula A = P * (1 - (1 + r)^-n) / r, where A is the annuity, P is the periodic payment, r is the interest rate, and n is the number of periods. First, determine the periodic payment, which is the amount of money paid or received at regular intervals. Then, calculate the interest rate and the number of periods. Finally, plug these values into the formula to find the annuity. **
-
What are the advantages and disadvantages of an annuity loan?
Annuity loans have the advantage of providing a predictable payment schedule, which can make budgeting easier for borrowers. Additionally, the interest rate is fixed, providing stability in the cost of borrowing. However, a disadvantage of annuity loans is that the interest payments are front-loaded, meaning that a larger portion of the payment goes towards interest in the early years of the loan. This can result in slower equity build-up in the early years of the loan. Additionally, if interest rates decrease, borrowers may miss out on potential savings as they are locked into a fixed interest rate. **
-
How do you calculate a variable interest rate annuity loan?
To calculate a variable interest rate annuity loan, you would first need to determine the initial loan amount, the interest rate, and the length of the loan. Then, you would need to calculate the periodic payment using the annuity formula, which takes into account the interest rate and the number of periods. The interest rate for a variable annuity loan may change over time, so you would need to use the current interest rate for each calculation. It's important to keep in mind that the total amount paid over the life of the loan will depend on how the interest rate fluctuates. **
-
What is the derivation of the formula for the annuity factor?
The formula for the annuity factor is derived from the present value formula for an ordinary annuity. The present value of an ordinary annuity is calculated by discounting each cash flow back to its present value and summing them up. The annuity factor is the result of this calculation, representing the factor by which the periodic cash flow needs to be multiplied to calculate the present value of the annuity. The formula takes into account the interest rate, number of periods, and the frequency of payments to determine the annuity factor. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.