Buy financetip.eu ?
We are moving the project
financetip.eu .
Are you interested in purchasing the domain
financetip.eu ?
domain@kv-gmbh.de · 0541-91531010
Buy financetip.eu ?
What is the flexible budgeting 2?
Flexible budgeting 2 is a budgeting approach that allows for adjustments to the budget based on changes in activity levels. It is an improvement over the original flexible budgeting method, as it takes into account different levels of activity and adjusts the budget accordingly. This allows for better planning and decision-making, as it provides a more accurate representation of costs and revenues at different levels of production or sales. Flexible budgeting 2 is particularly useful for businesses with fluctuating activity levels, as it helps to better manage resources and expenses. **
Can someone help me with business administration budgeting?
Yes, there are many resources available to help with business administration budgeting. You can seek assistance from financial advisors, accountants, or business consultants who specialize in budgeting and financial planning. Additionally, there are numerous online courses, workshops, and books that can provide guidance and practical tips for creating and managing a business budget. It's important to seek out help from professionals or resources that are tailored to your specific industry and business needs. **

Similar search terms for Reconstitute
Top-Angebote
Products related to Reconstitute:
-
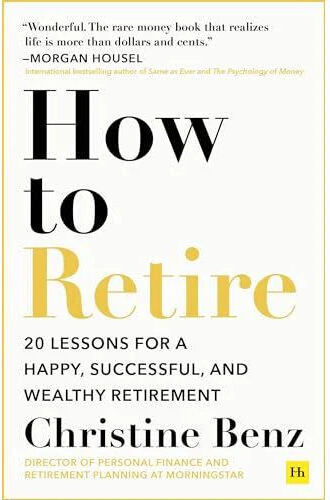
Harriman House How to Retire: 20 Lessons for a Happy, Successful, and Wealthy Retirement by Christine Benz - Paperback - Morningstar Retirement Planning GuideDiscover practical guidance for a happy, successful, and wealthy retirement with How to Retire: 20 Lessons for a Happy, Wealthy Retirement by Christine Benz. This non-fiction paperback, published by Harriman House, offers a collection of insights from twenty leading retirement thinkers. Drawing on interviews with these experts, Christine Benz distills the financial and lifestyle wisdom needed to navigate retirement with confidence. The book is essential reading for anyone approaching or already in retirement, or advising clients on making the most of their later years. Retirement is a profound life transition, and this book tackles both the financial and personal aspects with equal rigor. Rather than offering a single formula, Benz gathered the one lesson each of the twenty retirement thought leaders believe matters most for a successful retirement, resulting in a rich and varied collection of insights.11,99 £*Shipping: 2,99 £Secure redirect to the provider
-
Plata Publishing Rich Dad's Guide to Investing: What the Rich Invest In by Robert T. Kiyosaki - Paperback Personal Finance & Investing BookRich Dad's Guide to Investing: What the Rich Invest In is Robert T. Kiyosaki's essential companion to Rich Dad Poor Dad. This book takes readers deeper into the mindset and mechanics of building real wealth, focusing on active investing and how ordinary people can adopt the habits of the wealthy to escape the paycheck cycle. At the heart of this book is a simple but powerful distinction: passive investing versus active investing. Kiyosaki argues that true financial freedom comes from becoming an engaged investor who takes control of their financial future. This paperback is a valuable resource for anyone ready to move beyond saving and into investing, whether a beginner or someone already dabbling in stocks and property. Published by Plata Publishing, this book is aimed at adults and is a great companion to Rich Dad Poor Dad.10,99 £*Shipping: 2,99 £Secure redirect to the provider


-
Should teenagers be required to start saving for retirement at a young age? What arguments support this?
Yes, teenagers should be encouraged to start saving for retirement at a young age. By starting early, they can take advantage of compound interest and have more time for their savings to grow. It also instills good financial habits and responsibility from a young age, ensuring they are better prepared for their future. Additionally, with the uncertainty surrounding the future of social security and pensions, it is important for teenagers to take control of their own financial future. **
-
Why are value-added taxes considered indirect taxes and income taxes considered direct taxes?
Value-added taxes are considered indirect taxes because they are imposed on the consumption of goods and services, and the burden of the tax is ultimately passed on to the consumer through higher prices. On the other hand, income taxes are considered direct taxes because they are levied directly on individuals and businesses based on their income, and the burden of the tax cannot be shifted to someone else. This distinction is based on how the taxes are collected and who ultimately bears the economic burden of the tax. **
-
When is retirement?
Retirement typically occurs when an individual reaches a certain age, which is often around 65 years old. However, retirement can also be influenced by factors such as financial readiness, health considerations, and personal preferences. Some people choose to retire earlier or later than the traditional age, depending on their individual circumstances and goals. Ultimately, retirement is a personal decision that varies for each individual. **
-
Is retirement mandatory?
Retirement is not mandatory in most countries. It is a personal choice based on individual circumstances, financial readiness, and personal preferences. Some people choose to continue working past the traditional retirement age for various reasons, such as staying active, pursuing a passion, or maintaining social connections. However, some professions or industries may have mandatory retirement ages due to safety concerns or physical demands. **
How does investing in bonds differ from investing in a bank account?
Investing in bonds involves purchasing debt securities issued by governments or corporations, which pay a fixed interest rate over a specified period of time. In contrast, investing in a bank account typically involves depositing money into a savings or checking account, where it earns a variable interest rate set by the bank. Bonds generally offer higher potential returns than bank accounts, but they also carry a higher level of risk. Additionally, bonds have a maturity date, while bank accounts provide more immediate access to funds. **
Is it worth investing 129?
The worth of investing $129 depends on various factors such as your financial goals, risk tolerance, and investment horizon. If you are looking to start building a diversified investment portfolio, $129 could be a good starting point. However, it is important to research and consider the potential returns and risks associated with the investment before making a decision. Consulting with a financial advisor can also help you determine if investing $129 aligns with your overall financial plan. **
Top-Angebote
Products related to Reconstitute:
-
Cassell You're Not Broke You're Pre-Rich by Emilie Bellet - Paperback Personal Finance Guide for Adults - Budgeting, Saving & Investing Made SimpleGet straight-talking advice on personal finance with Emilie Bellet's guide to budgeting, saving, and investing. This practical book, designed for adults, helps you take charge of your finances and build lasting financial wellbeing, one manageable step at a time. Written by the founder of Vestpod, it distills years of expertise into an indispensable manual for anyone looking to simplify their finances and achieve financial confidence.6,99 £*Shipping: 2,99 £Secure redirect to the provider
-
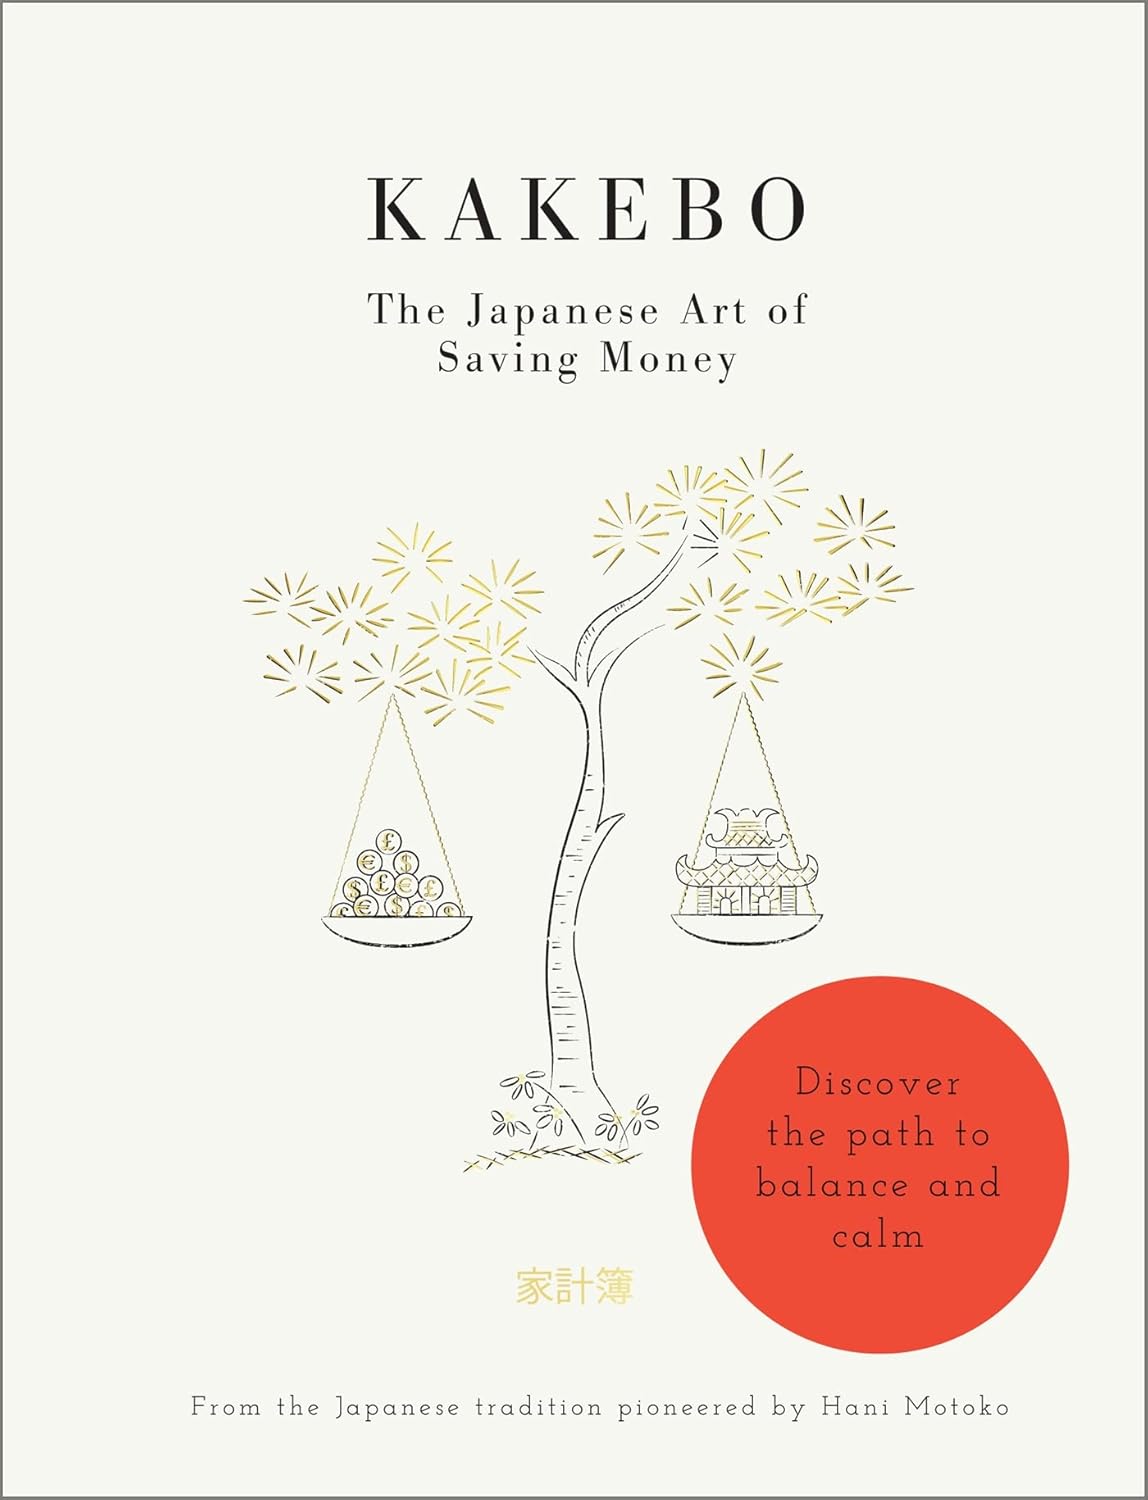
Short Books Kakebo: The Japanese Art of Saving Money by Hani Motoko - Paperback Budgeting Journal - Money Management Non Fiction GiftDiscover the Japanese art of saving money with Kakebo, a century-old budgeting journal brought to modern readers. Created by pioneering journalist Hani Motoko, this practical guide helps you set monthly savings goals, track weekly spending, and reflect on your relationship with money. It's an accessible alternative to budgeting apps, ideal for building lasting financial habits. Kakebo, which simply means 'household account book', distils a Japanese budgeting tradition that dates back to 1904. The beautifully produced paperback allows you to note your income, fixed outgoings, and savings target at the start of each month, then log spending across simple categories each week before tallying everything up.5,99 £*Shipping: 2,99 £Secure redirect to the provider
-
What is the flexible budgeting 2?
Flexible budgeting 2 is a budgeting approach that allows for adjustments to the budget based on changes in activity levels. It is an improvement over the original flexible budgeting method, as it takes into account different levels of activity and adjusts the budget accordingly. This allows for better planning and decision-making, as it provides a more accurate representation of costs and revenues at different levels of production or sales. Flexible budgeting 2 is particularly useful for businesses with fluctuating activity levels, as it helps to better manage resources and expenses. **
-
Can someone help me with business administration budgeting?
Yes, there are many resources available to help with business administration budgeting. You can seek assistance from financial advisors, accountants, or business consultants who specialize in budgeting and financial planning. Additionally, there are numerous online courses, workshops, and books that can provide guidance and practical tips for creating and managing a business budget. It's important to seek out help from professionals or resources that are tailored to your specific industry and business needs. **
-
Should teenagers be required to start saving for retirement at a young age? What arguments support this?
Yes, teenagers should be encouraged to start saving for retirement at a young age. By starting early, they can take advantage of compound interest and have more time for their savings to grow. It also instills good financial habits and responsibility from a young age, ensuring they are better prepared for their future. Additionally, with the uncertainty surrounding the future of social security and pensions, it is important for teenagers to take control of their own financial future. **
-
Why are value-added taxes considered indirect taxes and income taxes considered direct taxes?
Value-added taxes are considered indirect taxes because they are imposed on the consumption of goods and services, and the burden of the tax is ultimately passed on to the consumer through higher prices. On the other hand, income taxes are considered direct taxes because they are levied directly on individuals and businesses based on their income, and the burden of the tax cannot be shifted to someone else. This distinction is based on how the taxes are collected and who ultimately bears the economic burden of the tax. **
Similar search terms for Reconstitute
-
Harriman House How to Retire: 20 Lessons for a Happy, Successful, and Wealthy Retirement by Christine Benz - Paperback - Morningstar Retirement Planning GuideDiscover practical guidance for a happy, successful, and wealthy retirement with How to Retire: 20 Lessons for a Happy, Wealthy Retirement by Christine Benz. This non-fiction paperback, published by Harriman House, offers a collection of insights from twenty leading retirement thinkers. Drawing on interviews with these experts, Christine Benz distills the financial and lifestyle wisdom needed to navigate retirement with confidence. The book is essential reading for anyone approaching or already in retirement, or advising clients on making the most of their later years. Retirement is a profound life transition, and this book tackles both the financial and personal aspects with equal rigor. Rather than offering a single formula, Benz gathered the one lesson each of the twenty retirement thought leaders believe matters most for a successful retirement, resulting in a rich and varied collection of insights.11,99 £*Shipping: 2,99 £Secure redirect to the provider
-
Plata Publishing Rich Dad's Guide to Investing: What the Rich Invest In by Robert T. Kiyosaki - Paperback Personal Finance & Investing BookRich Dad's Guide to Investing: What the Rich Invest In is Robert T. Kiyosaki's essential companion to Rich Dad Poor Dad. This book takes readers deeper into the mindset and mechanics of building real wealth, focusing on active investing and how ordinary people can adopt the habits of the wealthy to escape the paycheck cycle. At the heart of this book is a simple but powerful distinction: passive investing versus active investing. Kiyosaki argues that true financial freedom comes from becoming an engaged investor who takes control of their financial future. This paperback is a valuable resource for anyone ready to move beyond saving and into investing, whether a beginner or someone already dabbling in stocks and property. Published by Plata Publishing, this book is aimed at adults and is a great companion to Rich Dad Poor Dad.10,99 £*Shipping: 2,99 £Secure redirect to the provider
-
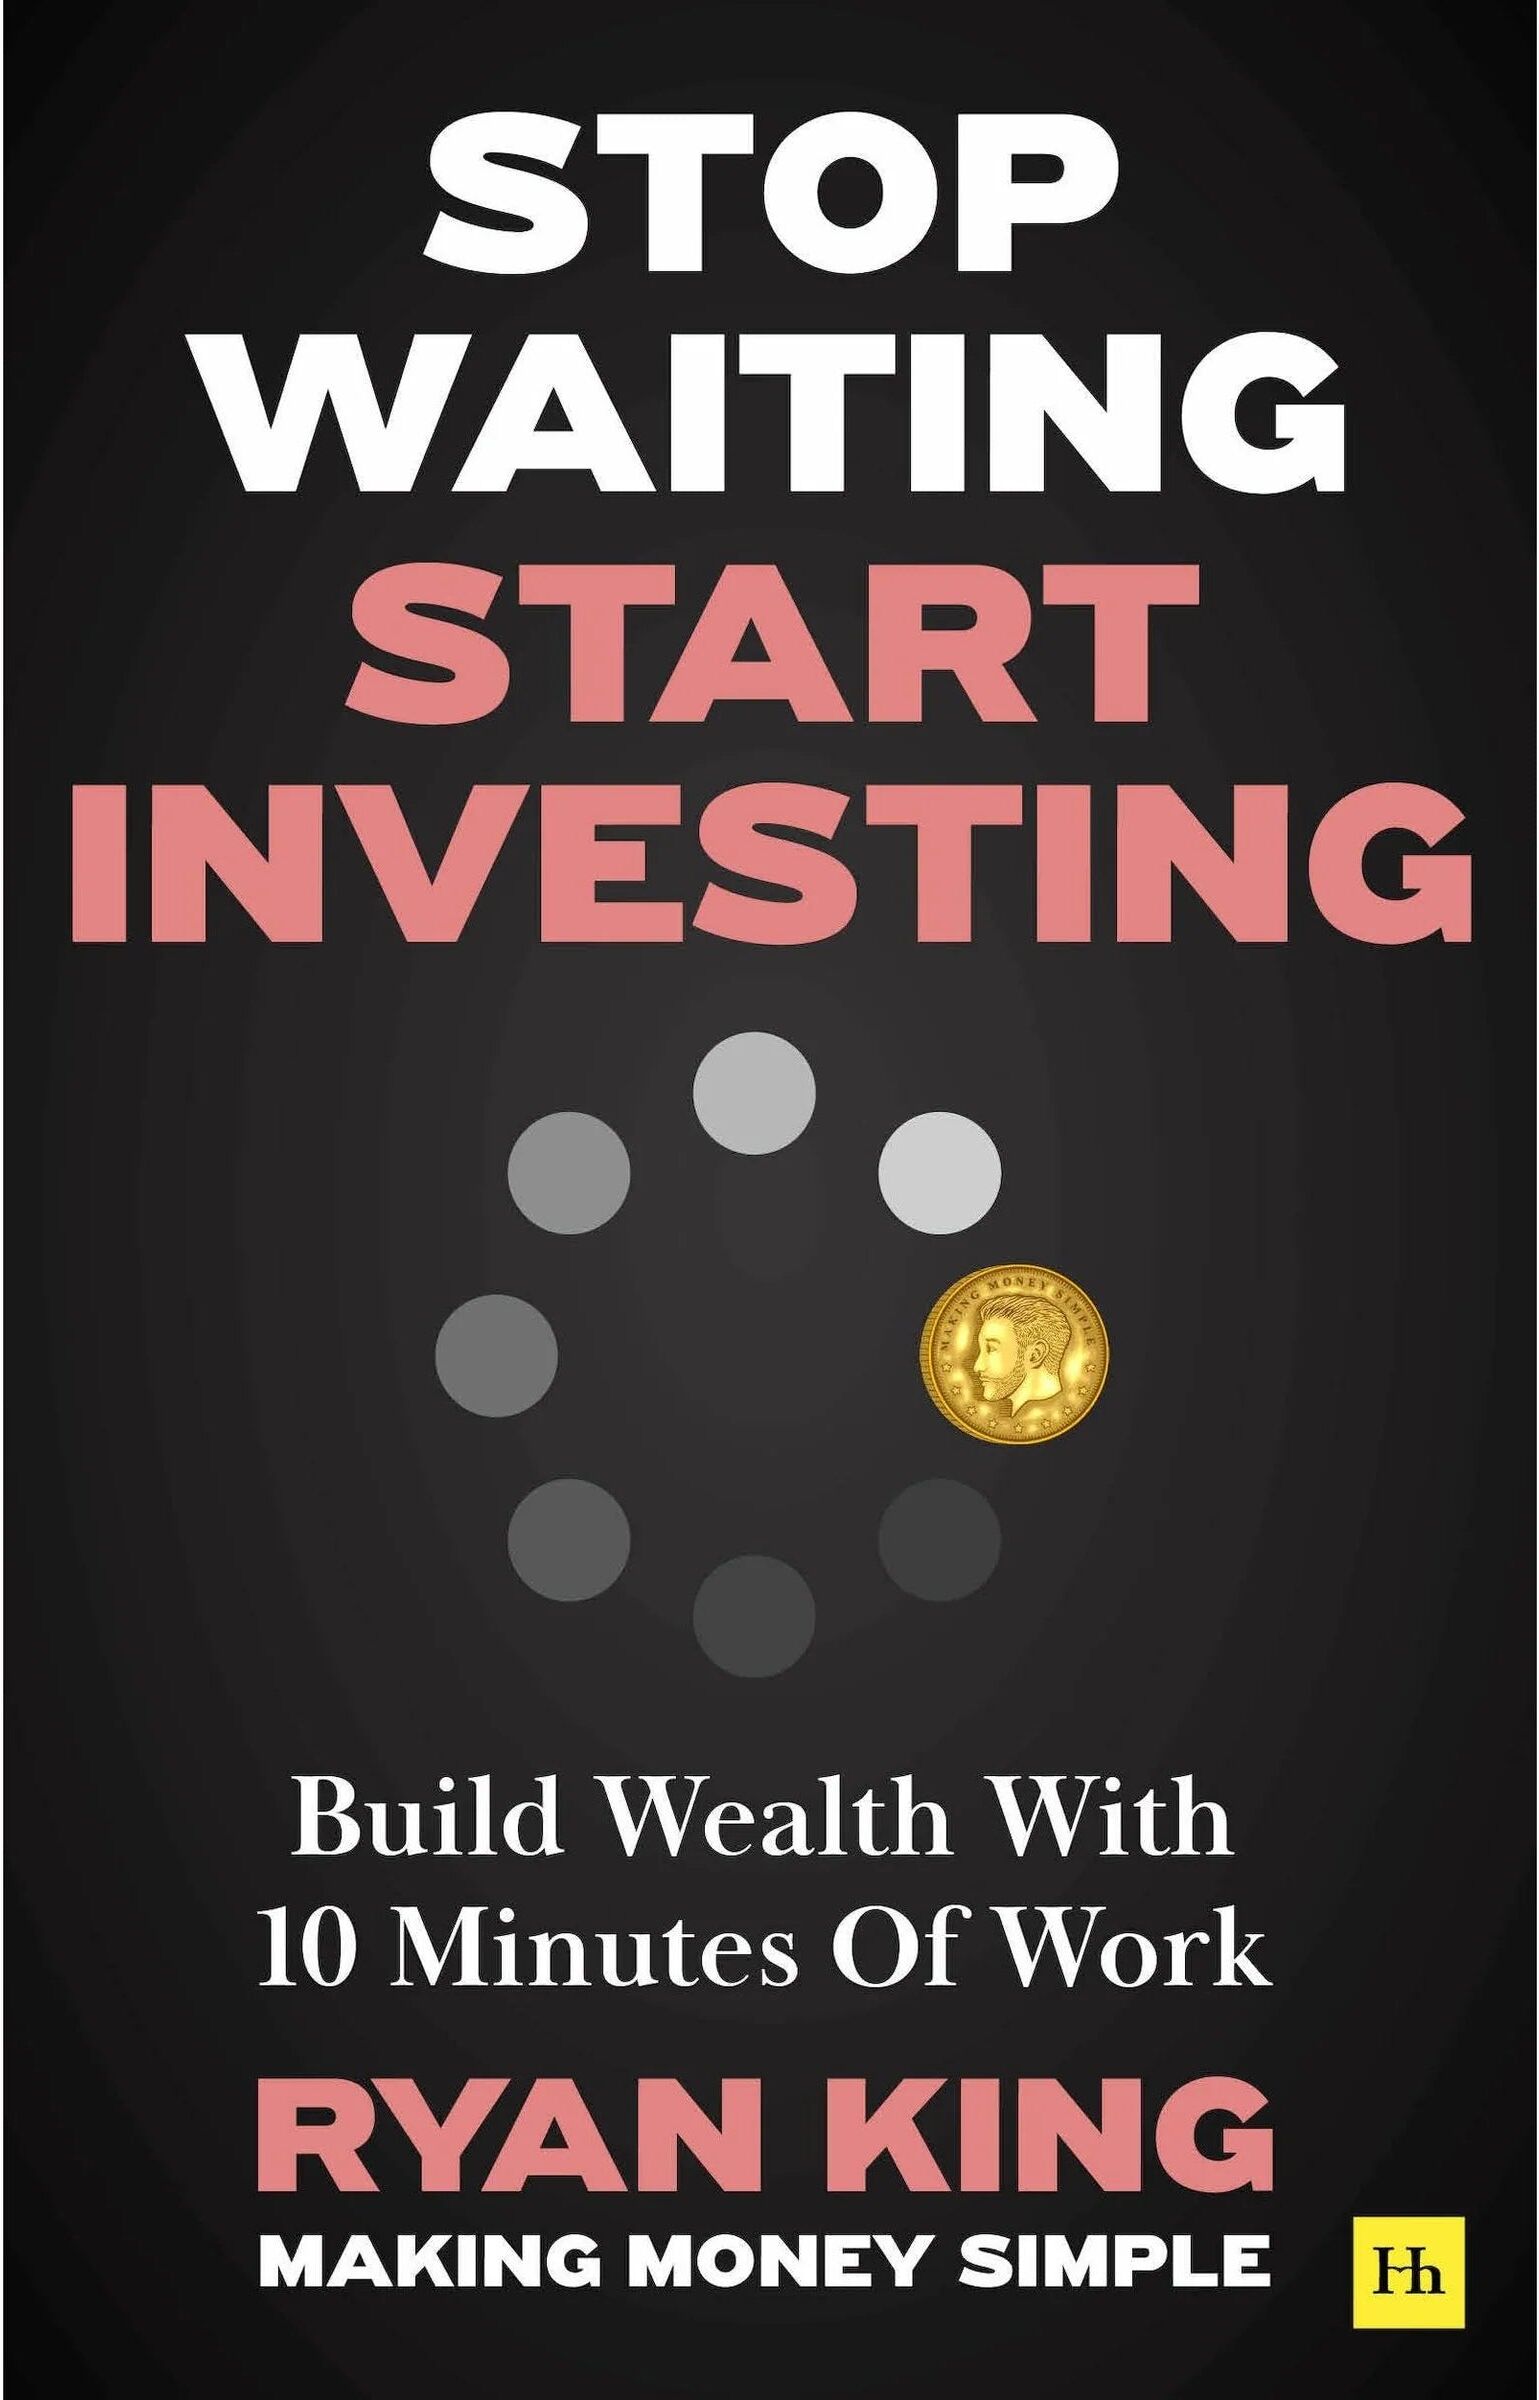
Harriman House Stop Waiting, Start Investing by Ryan King - Paperback Investing Guide - Build Wealth With 10 Minutes Of Work - Personal Finance BookBuild wealth with just 10 minutes of work a day using the stock market with this practical guide. Written by finance content creator and chartered accountant Ryan King, the book offers a simple, passive, automated approach to investing that fits around a busy life. Whether you're starting from scratch or refining an existing strategy, you'll be given the tools and confidence to take control of your financial future. This book directly addresses common hesitations about investing, guiding you step by step through the fundamentals of stock market investing in clear, accessible language. Ryan King draws on his own experience and expertise to provide a beginner-friendly guide to building long-term wealth.11,99 £*Shipping: 2,99 £Secure redirect to the provider
-
DK Your Financial Planner: Review, Plan, Reflect by Camilla Falkenberg - Female Invest Paperback Budgeting Workbook, Non-FictionYour Financial Planner: Review, Plan, Reflect is a hands-on companion from the founders of Female Invest, a platform that has helped millions of women take control of their money. This interactive planner builds on their bestselling guide to investing, turning financial theory into practical action. It's packed with worksheets, budgeting exercises, and goal-setting prompts to help readers save with purpose, invest with confidence, and build lasting financial independence. Written by Camilla Falkenberg, Emma Due Bitz, and Anna-Sophie Hartvigsen, the authors of the Female Invest movement, this planner provides the tools to put financial knowledge into practice. The book is suitable for adults (18+).4,99 £*Shipping: 2,99 £Secure redirect to the provider
-
When is retirement?
Retirement typically occurs when an individual reaches a certain age, which is often around 65 years old. However, retirement can also be influenced by factors such as financial readiness, health considerations, and personal preferences. Some people choose to retire earlier or later than the traditional age, depending on their individual circumstances and goals. Ultimately, retirement is a personal decision that varies for each individual. **
-
Is retirement mandatory?
Retirement is not mandatory in most countries. It is a personal choice based on individual circumstances, financial readiness, and personal preferences. Some people choose to continue working past the traditional retirement age for various reasons, such as staying active, pursuing a passion, or maintaining social connections. However, some professions or industries may have mandatory retirement ages due to safety concerns or physical demands. **
-
How does investing in bonds differ from investing in a bank account?
Investing in bonds involves purchasing debt securities issued by governments or corporations, which pay a fixed interest rate over a specified period of time. In contrast, investing in a bank account typically involves depositing money into a savings or checking account, where it earns a variable interest rate set by the bank. Bonds generally offer higher potential returns than bank accounts, but they also carry a higher level of risk. Additionally, bonds have a maturity date, while bank accounts provide more immediate access to funds. **
-
Is it worth investing 129?
The worth of investing $129 depends on various factors such as your financial goals, risk tolerance, and investment horizon. If you are looking to start building a diversified investment portfolio, $129 could be a good starting point. However, it is important to research and consider the potential returns and risks associated with the investment before making a decision. Consulting with a financial advisor can also help you determine if investing $129 aligns with your overall financial plan. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.