Buy financetip.eu ?
We are moving the project
financetip.eu .
Are you interested in purchasing the domain
financetip.eu ?
domain@kv-gmbh.de · 0541-91531010
Buy financetip.eu ?
How can I become a creditor?
To become a creditor, you can lend money to individuals or businesses in exchange for a promise of repayment with interest. This can be done through various means such as personal loans, business loans, or by purchasing bonds or other debt instruments. You can also become a creditor by providing goods or services on credit terms, allowing customers to pay at a later date. It's important to carefully consider the risks and potential returns of lending money before becoming a creditor. **
What is a debtor and creditor account management?
Debtor and creditor account management is the process of managing the accounts receivable and accounts payable of a business. It involves keeping track of the money owed to the business by its customers (debtors) and the money the business owes to its suppliers and other creditors. This includes monitoring payment schedules, following up on overdue payments, and maintaining accurate records of all transactions. Effective debtor and creditor account management is crucial for maintaining healthy cash flow and ensuring that the business meets its financial obligations. **

Similar search terms for Creditor
Top-Angebote
Products related to Creditor:
-
Penguin Rule #1: The Simple Strategy for Successful Investing in Only 15 Minutes a WeekPhil Town doesn't think so. He made a fortune, and in Rule #1 he'll show you how he did it.Rule #1:- Sets out the five key numbers that really count when you're buying stocks and shares- Explains how to use new Internet tools to simplify research- Shows how to exploit the advantages of being an individual investor- Demonstrates how to pay fifty pence for every pound's worth of business6,70 £*Shipping: 2,99 £Secure redirect to the provider
-
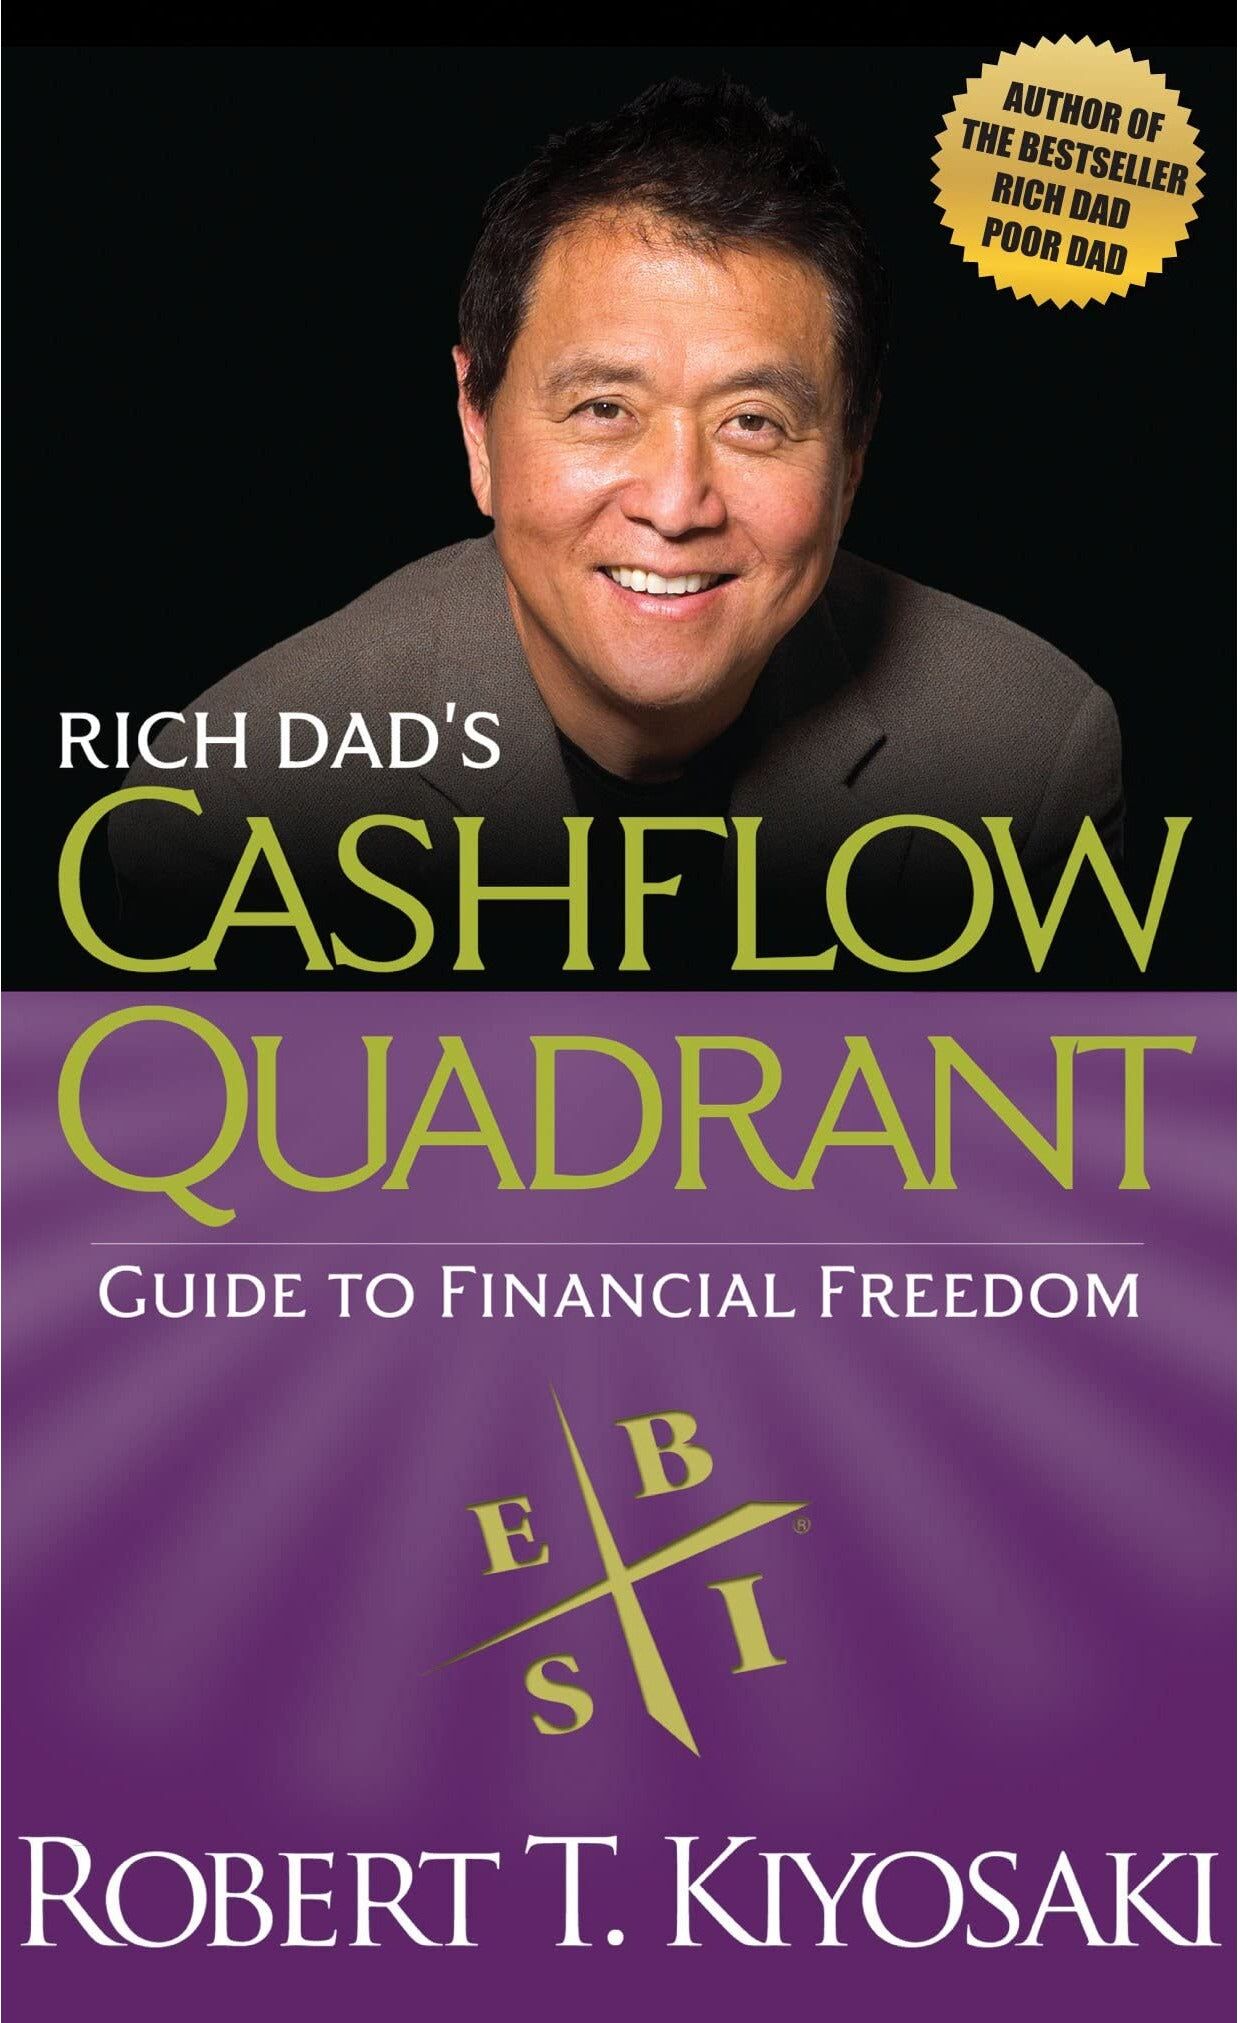
Plata Publishing Rich Dad’s Cashflow Quadrant – Robert T. Kiyosaki Guide to Financial Freedom, Investing & Wealth BuildingDiscover why some people work harder for money while others make money work for them with Rich Dad’s Cashflow Quadrant by Robert T. Kiyosaki. In this powerful follow-up to Rich Dad Poor Dad, Kiyosaki introduces the Cashflow Quadrant, a simple yet transformative framework that explains the four ways people earn income: Employee (E), Self-Employed (S), Business Owner (B), and Investor (I). The book reveals why true financial freedom is most often found on the B and I side of the quadrant. Through real-world examples and practical insights, Kiyosaki teaches readers how to shift their mindset, reduce financial risk, and build sustainable wealth through business ownership and investing. This book focuses on financial intelligence, passive income, and long-term wealth creation, rather than short-term gains. What You’ll Learn: The meaning of the Cashflow Quadrant (E, S, B, I) Why employees and self-employed people face financial limits How business owners and investors build passive income The mindset shifts required for financial independence How to move from job-based income to asset-based income Ideal for anyone serious about financial freedom, investing, and entrepreneurship, Rich Dad’s Cashflow Quadrant is a must-read personal finance classic.4,99 £*Shipping: 1,99 £Secure redirect to the provider
-
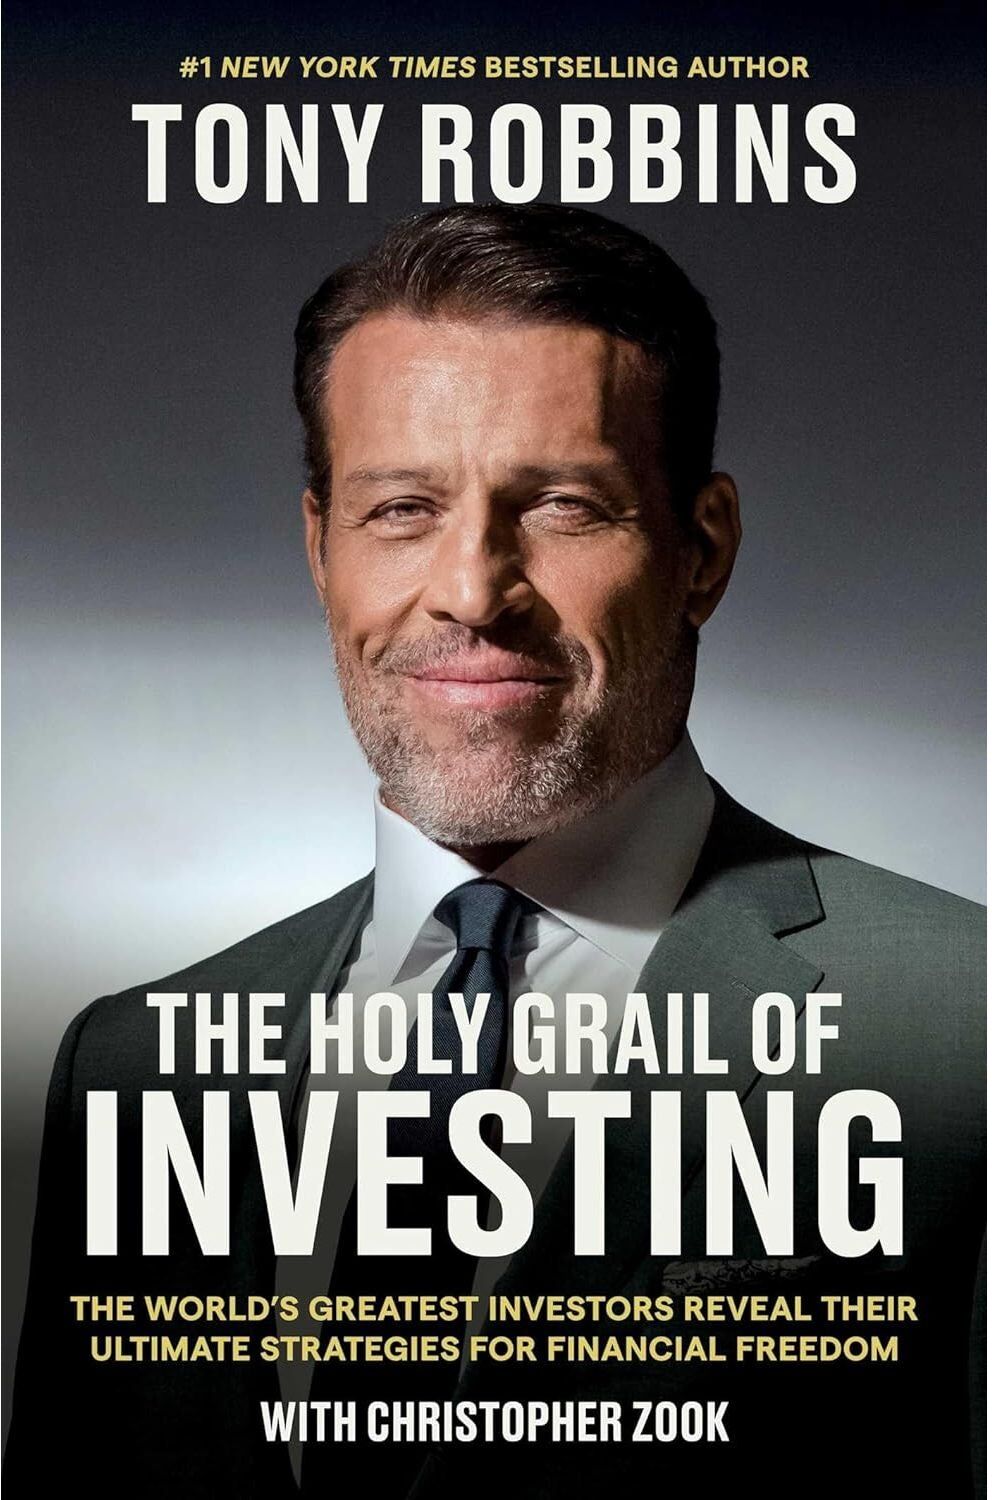
Simon & Schuster The Holy Grail of Investing: The World's Greatest Investors Reveal Their Ultimate Strategies for Financial FreedomTony Robbins, who has coached more than fifty million people from 100 countries, is the world’s #1 life and business strategist. In this new book, he teams up with Christopher Zook, a renowned financial investor who draws from thirty years of experience to round out the trilogy of #1 New York Times bestselling financial books. Together they reveal how, for decades, trillions of dollars of smart money – think of large institutions, sovereign wealth funds, individuals with ultra-high-net worth – have been making outsized returns using alternative investments in private equity, private credit, private real estate, energy and venture capital. Until recently, the vast majority of investors – those of us without insider access or eye-popping checkbooks – have been locked out of these exciting, high-yield opportunities. But there is a change underway. Alternative investments are coming to the masses, and investors need to know how to navigate their options, assess the merits of these opportunities, and determine how to best take advantage of this massive trend. In The Holy Grain of Investing, you’ll discover: Where opportunities will arise as we transition from the 'free money' era of zero interest rates to a new more realistic environment. How to take advantage of the trillions flowing into private investments by owning a piece of the firms that manage the assets. How to take advantage of private credit as an alternative (or compliment) to bonds. How and why professional sports teams have become an asset class of their own. How the renewable energy revolution will create new winners and losers. How investments in private real estate can work as an inflationary hedge. Interviews, advice, and insights from some of the world’s most formidable titans of industry, such as Howard Marks of OakTree Capital, Vinod Khosla of Khosla Capital, Barry Sternlicht of Starwood, Robert Smith of Vista, and Peter Theil of Founders Fund, among others. The market is changing, and the conventional wisdom no longer applies. Are you ready to add some fuel to your financial fire? No matter your wealth, your experience, your job, or your age, The Holy Grail of Investing will teach you everything you need to know to unleash the financial power of alternative investments.8,99 £*Shipping: 2,99 £Secure redirect to the provider
-
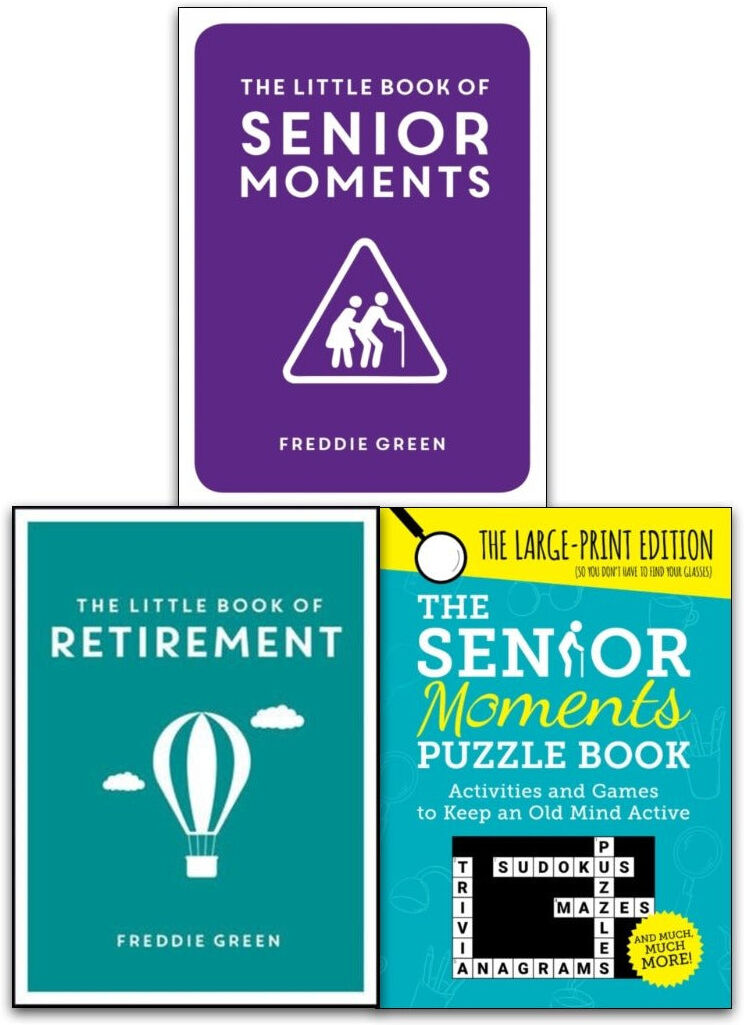
Summersdale Publishers The Little Book of Senior Moments, The Little Book of Retirement, The Senior Moments Puzzle 3 Books Collection SetTitles in the Set Are: The Little Book of Senior Moments The Little Book of Retirement The Senior Moments Puzzle Book The Little Book of Senior Moments You know you are having a senior moment when you decide it is time to pull up your socks, and realise you forgot to put any on If this sounds all too familiar, read on to discover whether your marbles just need a spring clean or you've well and truly lost them. The Little Book of Retirement You know you are retired when People from work keep phoning up asking where on earth you put important documents. The joys of retirement are many and varied, so read on to discover what makes these golden years so golden. The Senior Moments Puzzle Book Instead of wracking your brain for something to do, challenge your mind and have hours of fun with this delightful puzzle book. With everything from tricky crosswords, word searches, anagram puzzles and sudokus to simpler brain-teasers such as spot the differences, mazes and trivia questions, this large book edition means you will not even need your glasses wherever you put them.9,95 £*Shipping: 2,99 £Secure redirect to the provider

-
What is meant by creditor and what by debtor?
A creditor is a person or entity that is owed money or has provided goods or services on credit to another party. They are owed a debt by the debtor. On the other hand, a debtor is a person or entity that owes money to another party, typically a creditor. Debtors are responsible for repaying the money they owe to their creditors according to the terms of the agreement. **
-
How does a creditor settlement work at a bank?
A creditor settlement at a bank typically involves negotiating with the bank to settle a debt for less than the full amount owed. This can be done through a lump sum payment or a structured payment plan. The bank may agree to a settlement if they believe it is the best option for recovering some of the debt, rather than risking receiving nothing if the debtor defaults. Once a settlement is reached, the debtor will make the agreed-upon payment, and the bank will consider the debt resolved. It's important to note that settling a debt can have a negative impact on the debtor's credit score. **
-
Is the creditor the same as the bank account information?
No, the creditor is not the same as the bank account information. The creditor is the entity to whom a debt is owed, such as a lender, credit card company, or service provider. The bank account information, on the other hand, refers to the specific details of the bank account from which payments are made to the creditor. While the creditor is the recipient of the payment, the bank account information is the source of the funds. **
-
How can a debtor loss be converted into a creditor?
A debtor's loss can be converted into a creditor by the process of debt restructuring or debt settlement. In debt restructuring, the debtor and creditor negotiate new terms for the repayment of the debt, which may include a reduction in the total amount owed or a longer repayment period. In debt settlement, the debtor and creditor agree to a lump sum payment that is less than the total amount owed, in exchange for the creditor forgiving the remaining debt. Both of these processes can help the debtor to convert their loss into a creditor by satisfying the debt in a way that is more manageable for the debtor. **

What is meant by creditor and what is meant by debtor?
A creditor is a person or entity that is owed money or has provided goods or services on credit to another party. They are owed payment by the debtor. On the other hand, a debtor is a person or entity that owes money to another party, typically a creditor. Debtors are obligated to repay the amount owed to the creditor according to the terms of the agreement. **
Can someone please explain to me briefly the difference between creditor and debtor?
A creditor is a person or entity that is owed money by another person or entity. In other words, a creditor is someone who has extended credit or loaned money to another party. On the other hand, a debtor is a person or entity that owes money to another party. In other words, a debtor is someone who has borrowed money or received credit from another party and is obligated to repay it. In summary, a creditor is owed money, while a debtor owes money. **
Top-Angebote
Products related to Creditor:
-
Penguin Rule #1: The Simple Strategy for Successful Investing in Only 15 Minutes a WeekPhil Town doesn't think so. He made a fortune, and in Rule #1 he'll show you how he did it.Rule #1:- Sets out the five key numbers that really count when you're buying stocks and shares- Explains how to use new Internet tools to simplify research- Shows how to exploit the advantages of being an individual investor- Demonstrates how to pay fifty pence for every pound's worth of business6,70 £*Shipping: 2,99 £Secure redirect to the provider
-
Plata Publishing Rich Dad’s Cashflow Quadrant – Robert T. Kiyosaki Guide to Financial Freedom, Investing & Wealth BuildingDiscover why some people work harder for money while others make money work for them with Rich Dad’s Cashflow Quadrant by Robert T. Kiyosaki. In this powerful follow-up to Rich Dad Poor Dad, Kiyosaki introduces the Cashflow Quadrant, a simple yet transformative framework that explains the four ways people earn income: Employee (E), Self-Employed (S), Business Owner (B), and Investor (I). The book reveals why true financial freedom is most often found on the B and I side of the quadrant. Through real-world examples and practical insights, Kiyosaki teaches readers how to shift their mindset, reduce financial risk, and build sustainable wealth through business ownership and investing. This book focuses on financial intelligence, passive income, and long-term wealth creation, rather than short-term gains. What You’ll Learn: The meaning of the Cashflow Quadrant (E, S, B, I) Why employees and self-employed people face financial limits How business owners and investors build passive income The mindset shifts required for financial independence How to move from job-based income to asset-based income Ideal for anyone serious about financial freedom, investing, and entrepreneurship, Rich Dad’s Cashflow Quadrant is a must-read personal finance classic.4,99 £*Shipping: 1,99 £Secure redirect to the provider
-
How can I become a creditor?
To become a creditor, you can lend money to individuals or businesses in exchange for a promise of repayment with interest. This can be done through various means such as personal loans, business loans, or by purchasing bonds or other debt instruments. You can also become a creditor by providing goods or services on credit terms, allowing customers to pay at a later date. It's important to carefully consider the risks and potential returns of lending money before becoming a creditor. **
-
What is a debtor and creditor account management?
Debtor and creditor account management is the process of managing the accounts receivable and accounts payable of a business. It involves keeping track of the money owed to the business by its customers (debtors) and the money the business owes to its suppliers and other creditors. This includes monitoring payment schedules, following up on overdue payments, and maintaining accurate records of all transactions. Effective debtor and creditor account management is crucial for maintaining healthy cash flow and ensuring that the business meets its financial obligations. **
-
What is meant by creditor and what by debtor?
A creditor is a person or entity that is owed money or has provided goods or services on credit to another party. They are owed a debt by the debtor. On the other hand, a debtor is a person or entity that owes money to another party, typically a creditor. Debtors are responsible for repaying the money they owe to their creditors according to the terms of the agreement. **
-
How does a creditor settlement work at a bank?
A creditor settlement at a bank typically involves negotiating with the bank to settle a debt for less than the full amount owed. This can be done through a lump sum payment or a structured payment plan. The bank may agree to a settlement if they believe it is the best option for recovering some of the debt, rather than risking receiving nothing if the debtor defaults. Once a settlement is reached, the debtor will make the agreed-upon payment, and the bank will consider the debt resolved. It's important to note that settling a debt can have a negative impact on the debtor's credit score. **
Similar search terms for Creditor
-
Simon & Schuster The Holy Grail of Investing: The World's Greatest Investors Reveal Their Ultimate Strategies for Financial FreedomTony Robbins, who has coached more than fifty million people from 100 countries, is the world’s #1 life and business strategist. In this new book, he teams up with Christopher Zook, a renowned financial investor who draws from thirty years of experience to round out the trilogy of #1 New York Times bestselling financial books. Together they reveal how, for decades, trillions of dollars of smart money – think of large institutions, sovereign wealth funds, individuals with ultra-high-net worth – have been making outsized returns using alternative investments in private equity, private credit, private real estate, energy and venture capital. Until recently, the vast majority of investors – those of us without insider access or eye-popping checkbooks – have been locked out of these exciting, high-yield opportunities. But there is a change underway. Alternative investments are coming to the masses, and investors need to know how to navigate their options, assess the merits of these opportunities, and determine how to best take advantage of this massive trend. In The Holy Grain of Investing, you’ll discover: Where opportunities will arise as we transition from the 'free money' era of zero interest rates to a new more realistic environment. How to take advantage of the trillions flowing into private investments by owning a piece of the firms that manage the assets. How to take advantage of private credit as an alternative (or compliment) to bonds. How and why professional sports teams have become an asset class of their own. How the renewable energy revolution will create new winners and losers. How investments in private real estate can work as an inflationary hedge. Interviews, advice, and insights from some of the world’s most formidable titans of industry, such as Howard Marks of OakTree Capital, Vinod Khosla of Khosla Capital, Barry Sternlicht of Starwood, Robert Smith of Vista, and Peter Theil of Founders Fund, among others. The market is changing, and the conventional wisdom no longer applies. Are you ready to add some fuel to your financial fire? No matter your wealth, your experience, your job, or your age, The Holy Grail of Investing will teach you everything you need to know to unleash the financial power of alternative investments.8,99 £*Shipping: 2,99 £Secure redirect to the provider
-
Summersdale Publishers The Little Book of Senior Moments, The Little Book of Retirement, The Senior Moments Puzzle 3 Books Collection SetTitles in the Set Are: The Little Book of Senior Moments The Little Book of Retirement The Senior Moments Puzzle Book The Little Book of Senior Moments You know you are having a senior moment when you decide it is time to pull up your socks, and realise you forgot to put any on If this sounds all too familiar, read on to discover whether your marbles just need a spring clean or you've well and truly lost them. The Little Book of Retirement You know you are retired when People from work keep phoning up asking where on earth you put important documents. The joys of retirement are many and varied, so read on to discover what makes these golden years so golden. The Senior Moments Puzzle Book Instead of wracking your brain for something to do, challenge your mind and have hours of fun with this delightful puzzle book. With everything from tricky crosswords, word searches, anagram puzzles and sudokus to simpler brain-teasers such as spot the differences, mazes and trivia questions, this large book edition means you will not even need your glasses wherever you put them.9,95 £*Shipping: 2,99 £Secure redirect to the provider
-
Perfect Picks Market Portable Outdoor Solar Fire Starter Card Credit Card Sized Fresnel Lens Survival Tool Portable Outdoor Solar Fire Starter Card Credit Card Sized Fresnel Lens Survival ToolImagine having reliable fire anywhere the sun shines without matches or fuel. The solar fire starter card is a compact, walletfriendly survival essential that harnesses the power of sunshine to ignite tinder fast. Designed for campers, hikers, and...29,97 $*Shipping: 0,00 $Secure redirect to the provider
-
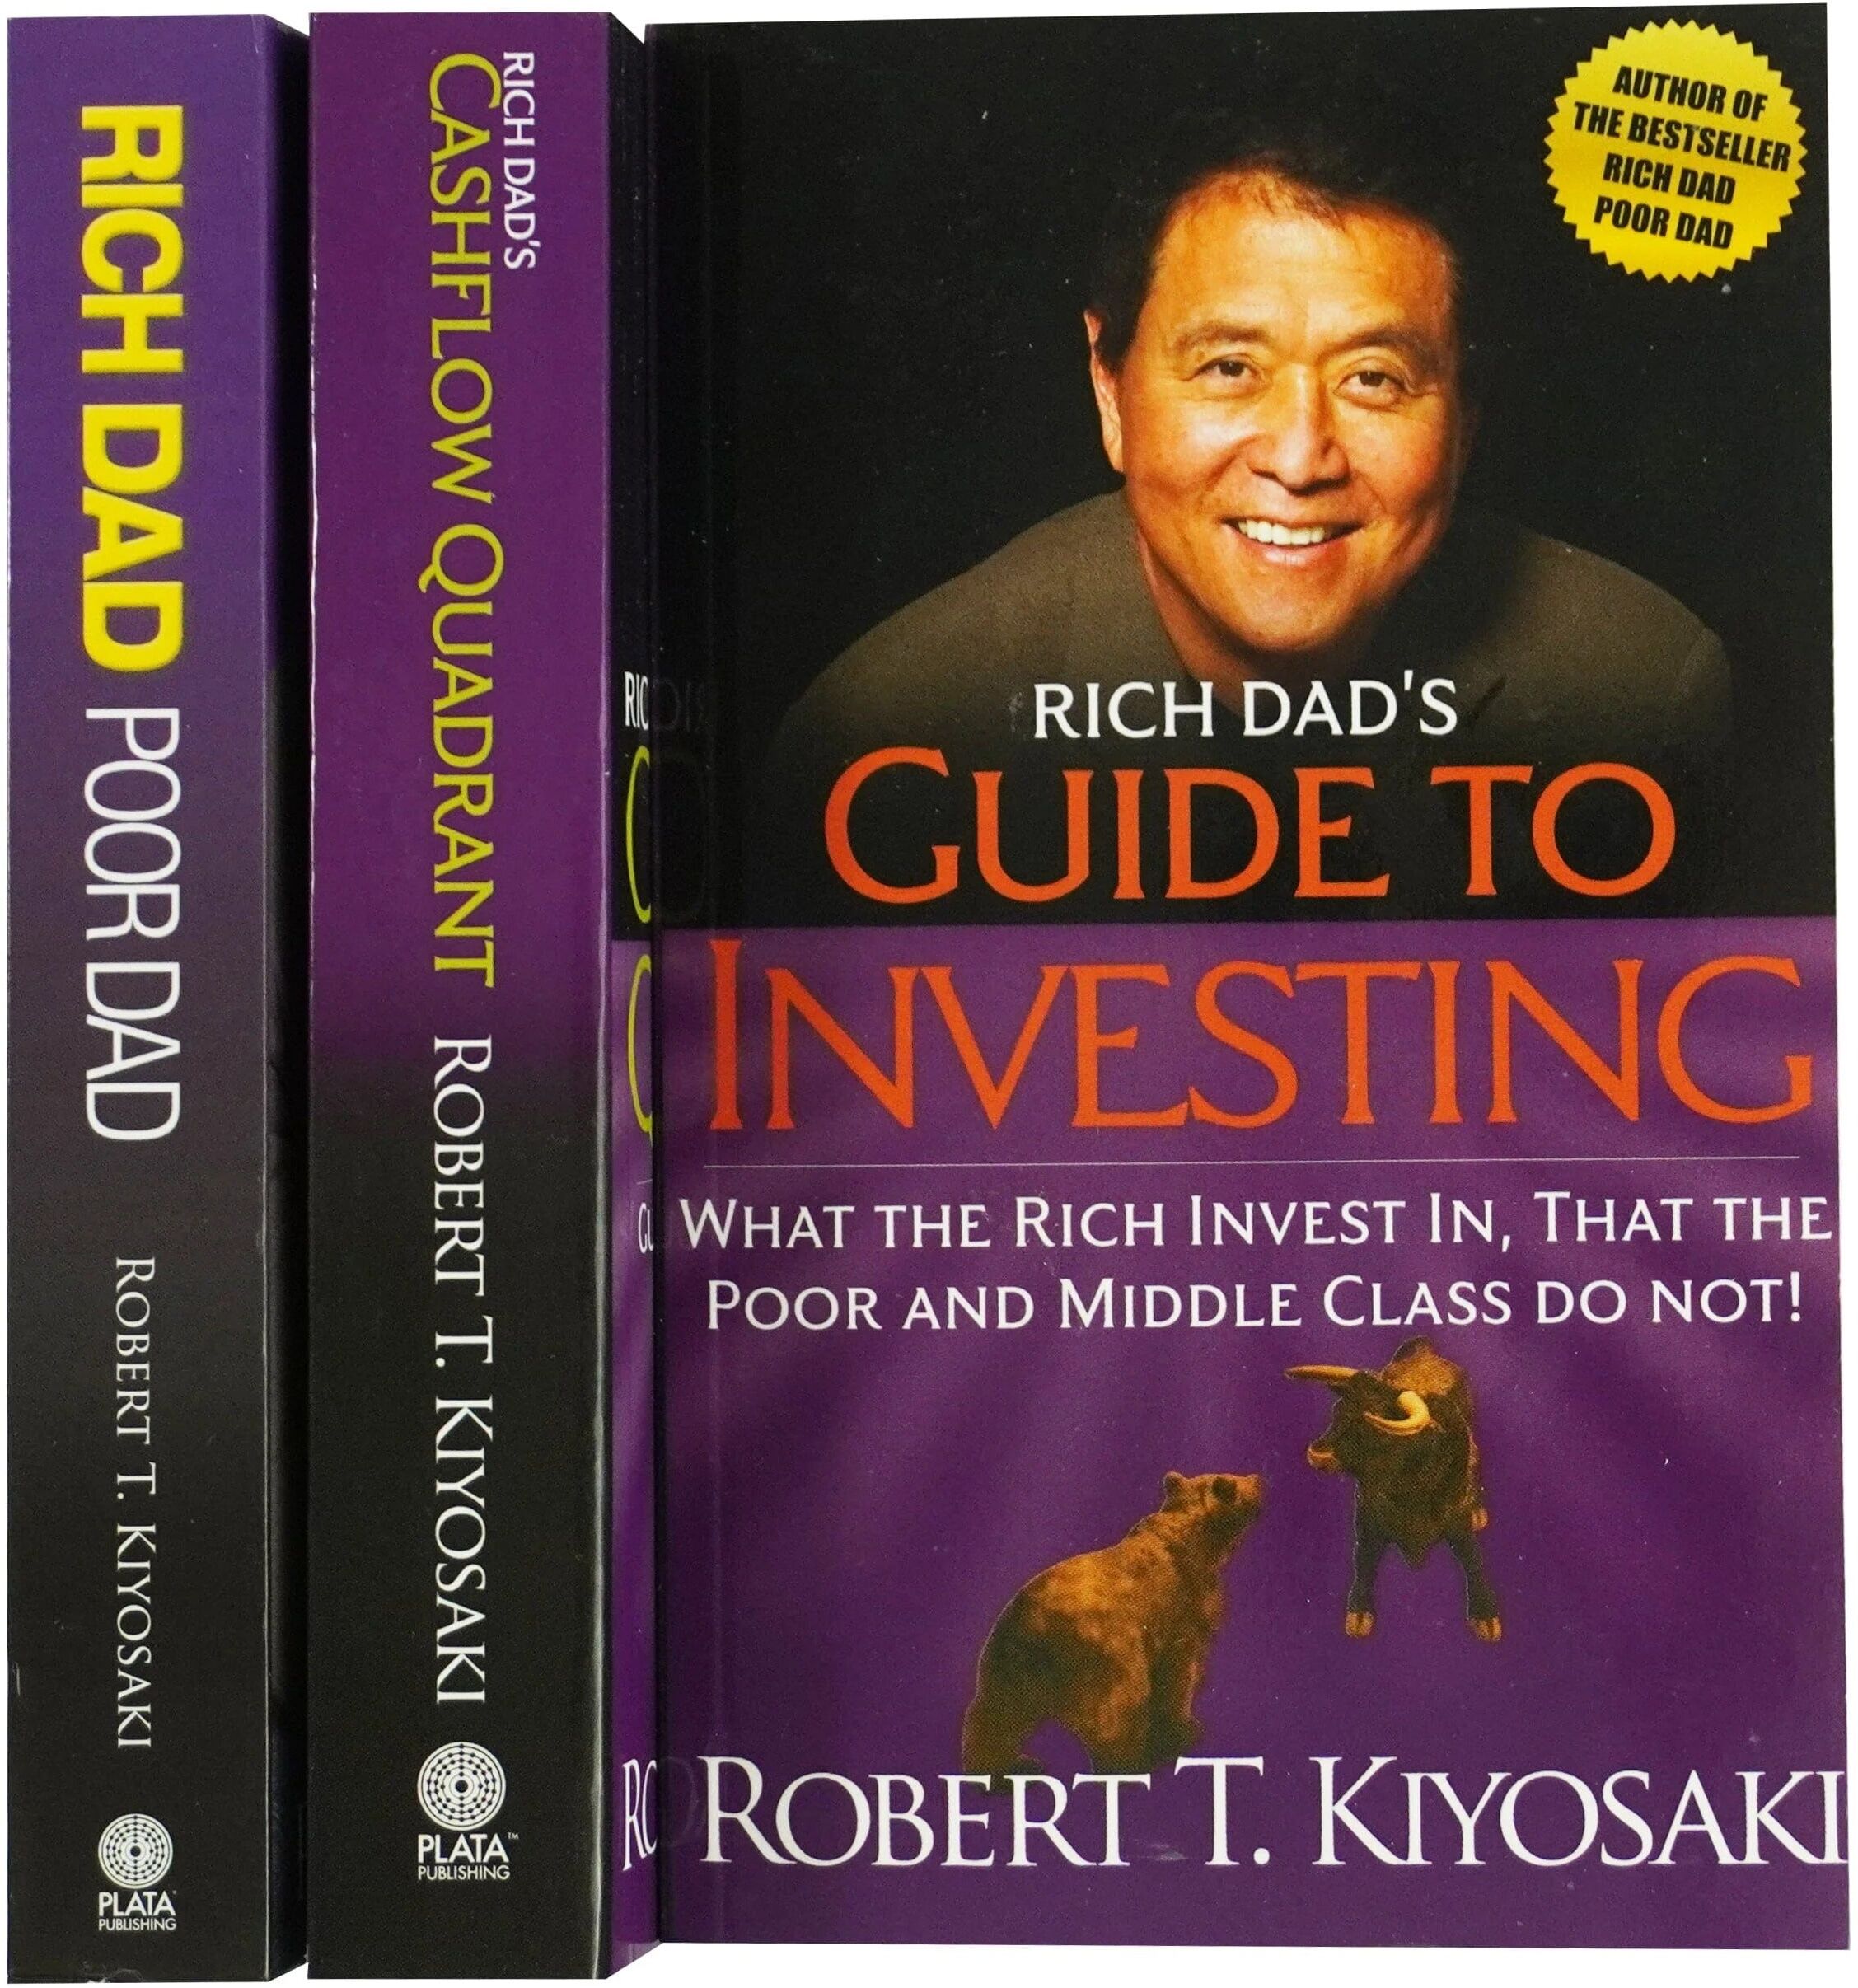
Plata Publishing Robert T. Kiyosaki Classics 3 Books Collection Box Set (Rich Dad Poor Dad, Cashflow Quadrant, Guide to Investing)Rich Dads Guide To Investing Investing means different things to different people… and there is a huge difference between passive investing and becoming an active, engaged investor. Rich Dad’s Guide to Investing, one of the three core titles in the Rich Dad Series, covers the basic rules of investing, how to reduce your investment risk, how to convert your earned income into passive income… plus Rich Dad’s 10 Investor Controls. Rich Dads Cashflow Quadrant Tired of living paycheck to paycheck? Learn why some people work less but earn more. Pay less in taxes, and learn to make their money work for them. It's simply knowing which quadrant to work from ― and when. The wealthy know that the keys to wealth and financial freedom are found on the right side of the quadrant, through business and investing. Rich Dad Poor Dad Rich Dad Poor Dad is Robert's story of growing up with two dads — his real father and the father of his best friend, his rich dad — and the ways in which both men shaped his thoughts about money and investing. The book explodes the myth that you need to earn a high income to be rich and explains the difference between working for money and having your money work for you. In many ways, the messages of Rich Dad Poor Dad, messages that were challenged and criticized 25 ago, are more meaningful, relevant, and important today than ever.11,89 £*Shipping: 2,99 £Secure redirect to the provider
-
Is the creditor the same as the bank account information?
No, the creditor is not the same as the bank account information. The creditor is the entity to whom a debt is owed, such as a lender, credit card company, or service provider. The bank account information, on the other hand, refers to the specific details of the bank account from which payments are made to the creditor. While the creditor is the recipient of the payment, the bank account information is the source of the funds. **
-
How can a debtor loss be converted into a creditor?
A debtor's loss can be converted into a creditor by the process of debt restructuring or debt settlement. In debt restructuring, the debtor and creditor negotiate new terms for the repayment of the debt, which may include a reduction in the total amount owed or a longer repayment period. In debt settlement, the debtor and creditor agree to a lump sum payment that is less than the total amount owed, in exchange for the creditor forgiving the remaining debt. Both of these processes can help the debtor to convert their loss into a creditor by satisfying the debt in a way that is more manageable for the debtor. **
-
What is meant by creditor and what is meant by debtor?
A creditor is a person or entity that is owed money or has provided goods or services on credit to another party. They are owed payment by the debtor. On the other hand, a debtor is a person or entity that owes money to another party, typically a creditor. Debtors are obligated to repay the amount owed to the creditor according to the terms of the agreement. **
-
Can someone please explain to me briefly the difference between creditor and debtor?
A creditor is a person or entity that is owed money by another person or entity. In other words, a creditor is someone who has extended credit or loaned money to another party. On the other hand, a debtor is a person or entity that owes money to another party. In other words, a debtor is someone who has borrowed money or received credit from another party and is obligated to repay it. In summary, a creditor is owed money, while a debtor owes money. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.